Sunday, June 24, 2018

Tuition as an investment


I read the news with increasing consternation that our society has created a monstrosity such as the tuition industry. The situation is now so bad that I think personal finance gurus need to put their heads together to formulate a better framework to decide whether kids should have tuition because the consequence to  your wallet is so dire that in the BIGS FB group, professional tutor La Papillon estimates about $1,500 spent per month for four subjects.

And this is only for one child.

Tutors have a guaranteed rice-bowl due to the systemic mess the education system has created for itself.

Teachers are overworked. They have administrative work to do and have to actually teach kids how to think and do their own research. This takes time away to teach kids how to pass exams.

At the other end of the spectrum, exams have to be pitched at a level harder than the material taught because the education system also has to sift through to the population to decide who gets to qualify for the most financially rewarding jobs. If exams test at the level of what was taught in school, we would need some kind of university entrance exam to sort out the cohort further.

This gives tutors an effective playground to operate on. Tutors don't ever have to teach critical thinking or how to even behave like a human being ( Although some do out of the goodness of their hearts ). Tutors specialise in helping kids survive the Academic Hunger Games of Singapore because that's what parents pay for. This means mechanically attacking every possible question that can come out in exams.

This is why rich families have a distinct advantage. Their kids have time to pick up critical thinking and new economy skills. Learning how to pass exams is simply a monthly pay-check to a tuition agency.

Not every parent has unlimited means. I will simply suggest a controversial idea here : Tuition is an investment. Basically, it is far superior to see tuition as a means of transferring your financial capital into your child's human capital. However, you need to understand that you are in essence converting your equity, cash and bond assets into a call option on the human capital owned by your child.

Your child needs to internalise what is being taught by a tutor for this call option to come into the money. This is the part which I can't really help with because every child is unique and I do know of some kids who simply don't benefit from tuition at all.

There are some consequences of employing such an approach to tuition :

a) The better you are as investor, the less tuition you should be willing  pay for.

This always gets parent's goat when I show them my numbers.

Suppose I take the $1,500 and invest it in a portfolio yielding 10% per annum for 15 years instead of paying for my child's tuition. As a consequence of that, the child fails to make it into a local university but gets a polytechnic diploma instead. I can, as a form of compensation, give him the entire portfolio of $630,000 on the day he starts his diploma job at $2,400. If the portfolio continues to generate 10% every year, your kid would have an effective starting salary of $2,400 per month + $63,000 per year.

This is way higher than the salary of a lawyer, doctor or engineer.

b) Even if you do not buy (a), limiting tuition can be profitable.

A lot of parents protest with my idea (a). One argument is that a fresh poly grad is the last person who should be handling such large sums of money. I can accept that. After all, parents know their kids best.

( I'm sure some kids will even declare financial independence and FIRE on the first day of work ! )

Suppose (a) is too hard to accept, then perhaps reducing tuition to just one key weak subject would some sense. This basically creates an asset allocation for your child that consists of tuition and the usual asset classes subject to the Mean-Variance portfolio concepts in Finance.

Future parents may even employ a tutor and a robo-advisor to look after their kids's future.

c) Even if you ignore this idea, you have to accept that tuition has limits.

The beauty of this idea is that investing in tuition now has logical limits. You will not invest in your children's education if returns to their human capital is too low compared to your returns on financial capital.  Otherwise, you are just subsidising a a tutor's lifestyle.

The value of a degree can be low if your kids insist on studying subjects which do not lead to steady professional jobs. There are NUS degrees with a starting pay as low as  that of a high-end private degree (many SIT degrees are worse). Worst, in the future, even a professional qualification may force some kids in the future to join the gig economy.

This is also balanced by existing high-paying jobs that do not require degrees such as real estate sales and being commercial pilots.

We need a new framework to assess a child's tuition needs and I would like to launch the first salvo in this new frontier in personal finance :

"Minimise tuition, invest the rest."

It is now time that we take the "Buy term, invest the rest" war-cry and drive it against the tuition industry !

The larger tuition franchises are now starting to sound like MLM companies and insurance firms, playing along the insecurities of parents to make an extra buck.

Before I end, I want to suggest a solution for policy makers. I think teachers should be allowed to get extra allowance for staying back in school to teach the weakest students in each subject. These students will have to pay for tuition within the school system but at a rate lower than the private sector, so it should be a voluntary scheme.

If every school transforms into a tuition agency after 3pm every day, the private enterprises will find it harder to wage psychological warfare against kiasu parents.




Thursday, June 21, 2018

My World Cup 2018 shenanigans...


Dungeons and Dragons geeks, as a general rule, are not into soccer.

Nerds and jocks do not mix.

For the life of me, I never understood why folks would bother so much about 22 guys kicking a ball while hordes of fans use the event as an opportunity to get drunk in a pub. It also irks me that whenever the English loses, wife abuse in England goes up.

After becoming an investor, though. I learnt that World Cup season is also bargain hunting season. So I started to follow the World Cup results because I wanted to know whether the market might recover during the semi-finals.

But this year, I have decided that things will be different.

To get some of my skin in the game, I started betting on the World Cup results.

Right now, I know nuts about football, but I do know that Brazil is the favorite to win  from the analysts in Goldman Sachs. I also know that the Economist seems to have projected Germany to be winners.

Being a total idiot to football betting.

I told my mum to buy $50 to bet on both Germany and Brazil to win the world cup, thinking to myself that if either team wins, I will be able to Wifi my home with Google Mesh technology.

But that was not to be.

Even in the best case scnario, a $50 bet on either Brazil or Germany would only win at best $200. My best case scenario would not even net one Google Wifi Router. In fact, it would not even cover the fees you pay to your cable provider to watch the World Cup in Singapore.

The MIT Technology review article pegs a Brazilian victory at 16.6% and a German victory at 12.8%.  Through the Kelly criterion, I can confirm that both my bets are a fools errand ( if you do it legally via Singapore Pools that is. )

The Kelly Criterion for the Brazilian bet is (4(0.166) - 0.834) / 4(0.166)) or -0.7%. The German bet will be even more disastrous.

Whenever the Kelly Criterion returns a negative number, it means that the bet is a pure gamble and investors are better off putting their money elsewhere.

So I guess I just have to appreciate the fact that I just bought myself a reason to follow World Cup 2018.

Anyway last Sunday, I finally gave up the idea of a Google Mesh Wifi, I bought a high end repeater at $150 and now enjoy a full 5 bars for my Home wifi.

Looks like I better stick to income investing.

Tuesday, June 19, 2018

The Art of the Good Life #27 : If you break on the outside.


The second part of the Circle of Dignity series is about maintaining the upper hand no matter what happens.

The example given was a story of a Vietnam veteran who was supposed to be paraded through the streets to show the world how well-treated US POWs were treated. Moments before he was supposed to be paraded, he bashed his face so hard against a stool, his face became bloodied so much so that the Vietnamese were no longer able to use him to make a public statement.

Although I sort of get this advice, I would hesitate to attempt such heroics. I mean, if I die, I would not be able to see my kids anymore. What's personal dignity anyway if you lose your chance to see your family in the end ? Instead, I think it's better to bend even if you sacrifice your personal dignity in the process.

But still, in my own little way, I am able to put a smaller principle into practice.

What I hate are sore losers when playing board games.

There is always this breed of gamer who overcompensates for his lack of real world achievementso he treats a gaming session as a matter of life and death.

My principle is that a sore loser should never be allowed to win board game, even if this means that I lose badly.

There was this Settlers of Catan game I played where the sore loser was on board. I clearly had the lowest point so I was losing badly. But before sore loser was about to win, I turned to a friend who was one point behind and asked him what resources he needed to get his last victory point. I then traded the resources for a nominal resource.

At my successful attempts at Kingmaking, the sore loser flew into a rage.

That remains one of the most satisfying board game experiences I ever had.

Saturday, June 16, 2018

Radical ideas on parenting.


This came about after I became triggered after reading Teo You Yenn's book when she created a false dichotomy on the various approaches to parenting found in Singapore.

For the folks that she did a lot of ethnographic research on, she labelled their approach towards children as seeing them as a "blessing". Children are almost like a gift from the Almighty. You take the children as they are and then do your best in raising them. Children for these folks are happy accidents.

Prof Teo had no mercy for the folks on the other side of the rich-poor divide. The label she applied to parents like myself is that we view our children as "projects". This is because we take a lot of pains to plan our families and put our kids through the education system.

By using two carefully chosen labels, Prof Teo was able to realign everyone's perspective on Singaporean parents. The good has become evil, and evil has become good.

If you have a kid out of wedlock, fail to get them into the best educational institutions and create the next generation of possibly very needy welfare recipients, you are forgiven because children are a "blessing" and society should ideally love every Singaporean unconditionally. If, like me, you take pains to ensure that your kids have a fully topped up Child Development account, we're suddenly soulless cogs in the machine who raise children our kids the same way a Project Manager meets a series of milestones. This is even when we're working hard so that our kids might become responsible tax payers in the future.

Another words, we're the 70% Sinkies responsible for everything horrible about Singaporean society today.

There are a lot of parenting gurus these days on social media. But to me, the only way to vindicate your ideas is that your own kids turn out well. And the truth is, there are no guarantees when it comes to our own kids. Kids are very creative in finding all sorts of ways to become a disappointment and disgrace to their families, so it's best to be humble, do your best but be prepared for the worst.

For today, I'm just going to offer alternatives from what you read from parenting gurus. I'm not trying to burst their bubble, because their kids may well win the Academic Hunger Games of Singapore. I just think that perhaps we can inject a lot more skepticism when we read what most of consider "common sense" when it common sense.

A key idea I take issue with is the idea that we should not give our children too much because it would sap their willingness to put in the hard work for their future and become overly entitled as Singapore citizens.

On careful inspection, it really does seem like common sense. We need to let children come to their own when they find work in the workplace. But I believe that I have valid reasons to be skeptical about this advice. I think that the folks spreading this idea, are the folks, who themselves, have received very much from their parents, so they might not be aware aware about how a little capital can go a long way in life.

Here are some of points that are worthy of consideration :

a) Children from richer families are better at delaying gratification.

This is possibly the most important discovery in social science of late. The orthodoxy is that children who can delay gratification seem to do very well in their adult lives. Buts someone tried to replicate the Stanford Marshmellow test lately,  and they found out in a bigger experiment that the kids who passed the marshmellow test came from richer families that was able to give them the stability and predictabiilty in their daily lives in such a way that they can delay something good to achieve something better in life.

b) Successful entrepreneurs tend to be rich kids with safety nets.

Another harsh truth is that the successful entrepreneurs are rich kids with safety nets. This actually makes sense if you are in the FIRE movement. The biggest risks I took throwing my IT career away to study Law in SMU simply cannot be performed by a family man who needs a day job. I need financial independence to be my enabler.

It's the same principle when you ask a young IT professional to forego a banking IT job to get into a startup. He'll do it if it is safe, otherwise, he needs an assurance if he were to survive a collapse of his startup. Coming from a rich family can provide that insurance from startup failure.

c) Investing requires experience and tuition fees.

This third point I have to share is that investing requires time. You need to have the courage to open a trading account, get a few trades out, lose a little money, but eventually figure out how to get a diversified dividend stream into your bank account.

It took me 14 years and over 7 digit portfolio to gain the courage to play with leverage. I have yet to even figure how to short a CFD.

Similarly, young investors might not be able to learn about all these tricks the Mr Market can offer to teach without a larger starting capital. Getting them to earn their way there can potentially work, but a larger starting capital can get them more comfortable to the idea of risk at a much earlier stage in life.

d) We may overestimate the job prospects for our children's generation.

It's very easy to say that Millenial's just need to be as hardworking and vicious as Gen X, but they are not coming into a job market with plenty of MNC and comfortable public sector jobs. Millenials may spend years holding jobs in the gig economy and face years of lumpy salary payments.

It's easy for me to say that kids should just build their passive income the same way I did, but I relied on decades of MNC employment to make it happen. Will these MNCs even be around in 25 years ?

P&G and HP are ghosts of their former selves.

In fact, I think believe the opposite compared to those "parenting gurus". I admit that given that my own kids are a work in progress, I can be wrong about parenting. But I believe that as it stands, what I am proposing is not inferior to what other parents are touting.

Rather than to just leave our kids to slug it out, I believe the following alternatives may work but might be controvesial:

a) Tuition money can invested into a financial portfolio if the gains in human capital are low compared to gains in financial capital.

For this point, you need to understand your kid's character.

Not all kids are academically brilliant. $1,500 invested in a top flight tuition every month may send some kids to Raffles Institution or GEP, but other kids with the same investment can still end up in Changkat Changi Secondary School.

Not all kids respond well to expensive tuition and hot-housing.

However, the opportunity cost of paying for tuition is investing in the financial markets. A good backtested portfolio can reasonably return 9% every year. If your kid cannot graduate from a good local university, he might do better with a portfolio that generates passive income along with a polytechnic diploma instead.

b) Give your kids an early inheritance while you are still alive to supervise them.

There are too many stories of useless adults in their 30s waiting for their parents to die so that they can become financially independent. The common sense solution is not to give these useless bastards anything.

But I think the solution may the opposite of that approach

While a parent is alive, why not give your children small amounts of capital so that they can learn how to handle larger sums of money, which really requires a different mindset from wage slavery anyway.

Personally, I would give around $50,000 on graduation day and negotiate a cash award for every level of CFA my kids are able to conquer. This would get them to become more confident with handling a market portfolio and given them an incentive to take on one of the hardest exams the world has to offer.

Imagine other Millenials struggling with their study loans but your kids are figuring out how diversified portfolio of REITs can pay off some of their daily expenses so they know that alternatives to earned employment exists. That's a genuine competitive advantage.

Anyway, do share your feedback on these controversial ideas I'm pretty open to criticism because I have two decades to refine these ideas while my own children grow up.


Monday, June 11, 2018

The Art of the Good Life #26 : But If Not

This is a really tough chapter for me to grasp, so I will keep it short.

The author believes that everyone should develop a circle of dignity. One component of this circle of dignity is to have a set of principles that you absolutely commit to,  so much so that even rational argument would not be able to displace it.

I struggle with this principle largely because I do not have a religion, so beyond my immediate family, I don't have many principles which are not subject to negotiation or rationalisation. I also believe that a large number of the world's problems comes from this form of inflexibility. Sooner or later, you will meet someone whose principles are diametrically opposite to yours.

For example, while I have steadfastly refused to spend my capital, this is not a principle I would stick to if my kids need to get an education.

Perhaps the reader can share with me some of the principles you hold so dear that even a logical argument will not cause you to violate this principal.

This is truly out of my depth !


Saturday, June 09, 2018

A deeper analysis of the Astrea IV Private Equity Bond Offerings.

There seems to be quite a bit of excitement on the Astrea IV Private Equity Bond Offerings.  These bonds have been described in great detail by other bloggers such as Investment Moats and Financial Horse.

I just wish to write a small article to plug the gaps in the analysis I find in the blogosphere. Compared to most investors, my personal interest lies in the Class B rather than the Class A offerings.

Here I am detailing the reasons why this is the case.

[ Feel free to critique my analysis. In practice, I do not have the money to move into this asset class this year but I expect some leveraged positions to be take place a few years later after more of such offerings start appearing in the market. This is definitely going to be a successful new asset class that retirees and income investors to flock to moving forward. ]

a) Class B offering actually has lower interest rate risk

Here's where some bond investing fundamentals taught in CFA class may come in useful. The biggest issue investing in bonds is rising interest rates over the next few years. This makes interest rates the primary consideration when you think about buying Astrea IV bonds.

A lot of bloggers miss out on a discussion about bond duration, which measures how sensitive the bond prices are to slight changes in interest rates. I used my spreadsheet and did a simple calculation of the Macaulay duration for the Class A1 and Class B bond offering.

For the Class A1 bonds, I estimated the bond duration to be around 8.31 years.

For the Class B bonds, I estimated the bond duration to be around 7.59 years.

What this means is that for every 1% rise in interest rates, your Class A1 bonds will lose about 8.31% in market value, but the Class B bonds will lose only 7.59%. This is because Class B bonds give out a higher coupon rate allowing you to recoup your costs at an earlier date resulting in a less swingy experience.

b) Class B bonds can achieve this lower interest rate risk at a higher risk of default

The other aspect of bond investing is credit risk. The Class A-1 bonds are rated A by Fitch. For this  A credit rating, I can't seem to find a default rate on Wikipedia, but I think it is reasonable estimate it at a cumulative 1% over 5 years or close to 2% over 10 years. For the Class B bonds, the rating is lower at BBB that gives it a default probability of around 2.11% over 5 years, we can round it up to 5% over 10 years.

After performing this analysis, I am actually a lot more attracted to the idea of buying Class B bonds for their higher coupons using 200%leverage. Kim Eng brokers are offering me at a financing rate of 2.5%, so at 200% leverage, I'm looking at a delicious 11% yield every year that offsets the rising interest rates that will affect the market price of these bonds. The downside is a 5% chance of busting out over the next decade and fluctuations in USD currency (which I have yet to quantify).

Anyway, my hands are still full trying to build my leveraged REIT portfolio. At a much later date, I will come back to to my duration calculations when I get an indicative price of how much these bonds will trade in the secondary markets.

My calculations also reveal that perhaps in future PE bond offerings, retail investors get exposure to the riskier tranches because the credit default risks are often offset by lower interest rate risk. The Class B bonds may require a position size of $100,000 for a 200% leveraged position which is an amount of money that most retail investors do not have.

Anyway, let me know what you think of my analysis.


Thursday, June 07, 2018

F.U. Money is about reinventing the Singapore Dream !

This post came about because Kyith Ng from Investment Moats was giving me feedback on my slides for the upcoming talk and he wants me to see if I can suggest some alternative lifestyles or schemes for people to choose from after they achieve their financial independence.

After some deliberation, I think we can do much than that.

I think by now, readers of this blog knows that I've been blogging about the Death of the Singaporean Dream for quite some time. In fact, I think the Dream is already Dead. My generation's leaders murdered the Singaporean Dream when hordes of foreigners were allowed in to keep our salaries depressed. Now the Millenials don't buy the Dream at all, they know it's a Faustian bargain which is why they chose work-life balance over career ambitions.

Why ?

Because Gen-X knew what betrayal feels like.

Opponents of inequality talk about small differences in a family environment being magnified into serious socio-economic gaps in adulthood.  So much so that Low SES and High SES jokes are quite the norm in social media. It also does not look good that folks in their 40s face a serious threat from automation and technological shifts.

The first victim of social upheaval at such a profound scale is the older model of successful Singapore living which is that idea that, upon graduation, we can have hold a job for about 30 years and then start a family in the meantime. In reality, most of our careers will not even be half as long as our mortgage tenures. And yet the prices of housing continue to edge up due to the presence of foreign buyers.

A new schema for the Singaporean Dream needs to incorporate the latest and greatest in the field of Personal Finance so much so that F.U. Money is now more important than ever if you wish to craft a New Singapore Dream for yourself.

Tools to create your own Singaporean Dream needs to incorporate the following :

a) It has to be achieved faster and not slower.

While its great to delay gratification, our generation has less time than before. Our STEM degrees become worthless in half the time compared to the 1990s. Humanities degrees do not even command value right off the gates. Mathematical models allow speed to be achieved with a reasonable risk of ruin. We're becoming obsolete by the minute even as we hold day jobs. This is because different parts of the industry automate at different rates.

b) It has to be indifferent to paper qualifications

The workplace is full of biases that pay private degree holders about $1,200 less than local degree holders. For the winners of the academic race, that's fine and good. For the losers, they need to find a playground where they can be safe from discrimination based on academic achievement. The markets are fair arbiters of investment skills. I have never seen a stock pay a lower dividend to a private degree holder than local degree holder. Of course, if you receive poor training, you might not have the knowledge to buy the right stock in the first place.

c) It should be rewarding even if it's not done 100% right

Shooting for $2,000 per month in passive income is sweet but a lot of people will fail in achieving this mission. The trick is not to mislead the audience into thinking that it's easy. Saving 80% of your take home pay is as hard as playing championship sports. The trick is that meeting 10% of your goal should be rewarding as well. $200 in passive income every month can pay off your public transport expenses.

I'm still in the process of refining my slides.

If there is anything you'd like me to specifically address, feel free to share about it here.


Tuesday, June 05, 2018

The Art of the Good Life #25 : Hedonism and Eudemonia


My talk on F.U. Money is not just going to be a showcase of reams of data in my back-testing experiments. In fact, I'm spoiling one of my slides here ( I have close to 60 slides for the 30 minute presentation ).

Post- F.U. Money, most folks will focus on personal pleasure or Hedonism. These are the guys inflicting all that psychic damage on me right now, posting their wonderful June Holiday photos of them travelling with their kids in Europe. Hedonistic people will use their money to travel, procure more sex, or eat at a Michelin 3-star restaurant. It's their money, and they've earned the right to enjoy themselves.

But philosophers are not satisfied with a life filled with nothing but pleasure.

I was enlightened by an intern yesterday that the best movie on IMDB is the Shawshank Redemption. Movies like the Infinity War make a hell of a lot of money, but why do such movies never make it as great movies that withstand the test of time? Simple. The Shawshank Redemption is a lot more meaningful as compared to Infinity War which is just a CGI extravaganza.

A meaningful life explains why some people post financial independence would prefer to make a dent in the universe instead of retiring to a life of seeking endless pleasure.

After getting your F.U. Money, you should be seeking both Hedonia and Eudemonia. Do find things to do that make life pleasurable.

Your financial independence is also the time to ask the hard questions of what makes life meaningful to you. For many folks, it's raising their kids well. For others, it might be devoting to a cause greater than yourself. 

Sunday, June 03, 2018

An idea so dumb, only an intellectual will believe it !


The genesis of this article came from Alvin Chow of Dr Wealth who make this quote of social media. I was once reminded of the Efficient Markets Hypothesis (EMH). On Investopedia, the definition of EMH is as follows :

"The efficient market hypothesis (EMH) is an investment theory that states it is impossible to "beat the market" because stock market efficiency causes existing share prices to always incorporate and reflect all relevant information."

This theory is broken down into three sub-forms:

  • The weak form of EMH posits that past movements and volume do not affect future stock prices. Believers in the weak form do not believe in Technical Analysis.
  • The semi-strong form of EMH posits that stock prices incorporate all public stock information. Believers in the semi-strong form do not believe in Fundamental Analysis and Technical Analysis.
  • The strong form of EMH posits that stock prices incorporate all public and private information. Believers in the strong form of EMH do not even believe in insider trading !
( I used to subscribe to the weak form of EMH until really recently, making myself one of the intellectuals who believe in this theory. )

But I'm not afraid to change my ways if more profitable approaches are out there.

For the past week, I have been going to library to prepare for the talk on F.U. Money, and I have some backtesting insights that I can leave for readers of this blog that would not detract from the really interesting findings for the paying customers of this upcoming event.

In short, here's what I found :

The baseline gains you can make from the STI ETF has been around 4.4% for the past 10 years. 

If you employ a filter that chooses Singapore stocks with lowest EV/EBITDA  and then find within this universe, those with the highest ROIC, you can get a 10.63% return with a Sharpe ratio of 0.39. 

Not too bad. 

At this stage, a lot of investors will be satisfied with this filter because it can achieve decent gains. But when you combine a value measure with momentum indicator like the Relative Strength Indicator (RSI), I was able to achieve 24.89% returns with a Sharpe Ratio of 0.9. 

As all my backtests experiments span 10 years, we clearly cannot ignore some of the ideas of Fundamental analysis as well as Technical Analysis.

This makes the EMH one of those theories that is so dumb, only intellectuals will believe in them. 


Thursday, May 31, 2018

BIGScribe Investors Exchange 2018 is about F.U. Money !


I'd like to see BIGScribe Investors Exchange as the Wrestlemania of Singapore Investing.

You can book your tickets for this event here.

Our last event sold out and I was told by the event organisers that we are selling the tickets at twice the rate last year. It's no surprise, because as of this time, we have four heavyweight speakers who will be talking about serious investing topics for that day.As you all know, I am a retail investor and a fan boy, so I look forward to the presentations just like members of the audience.

Which puts me in a fix, because I am the fifth speaker.

Traditionally the last speaker in a presentation team in SMU Law School presentations has to find a way to wrap up the proceedings and create a positive spin for the whole event. Even in Wrestlemania, the final event is when the Heavyweight title often changes hands. The wrestlers in the final event is seldom the best fighter in the WWE ( Leg Drop of Doom, anyone ? ), but the fight has to contain the best trash-talking and drama.

Last year, the topic of my speech was "50 Shades of Dividends Investing" and I was quite sure some folks were offended by my subject matter.

This year may be no different.

I will be talking about F.U. Money.

But for now, I'd like what F.U. stands for to be a mystery.

I will discuss what F.U money is, how to get it, how to make it grow. I will explain why we are so hot and bothered by F.U money. Why we want that F.U. moment in our lives and why we need to get that moment soon and not delay gratification indefinitely.

As in all my talks, I will discuss some empirical observations on blue chip stocks, dividends and REITs.

If you're lucky :

a) You might even become disillusioned and even a little angry with ETFs.
b) You may also never see some degree programmes the same way again after my talk.
c) You suddenly feel that contrary to modern concepts of self-help, delaying gratification has limits.

You see, my job should not be just to motivate you, my job is to show that you reality bites and how you can fight back.

Folks who follow me will expect that I try to back up every assertion with research and empirical findings to support my thesis. A lot of material was crunched to create the slides which are undergoing trimming right now.

We will take the data science of investing and try to marry it with the latest psychological research and I will show you how all this can be tied up to your personal goals of happiness and bliss. 

It's time for Investors Exchange 2018.

Buy the tickets while stocks last.

And most of all - F.U. !!!


Tuesday, May 29, 2018

Describing a problem well does not mean that you have a solution.

The Art of the Good Life is taking a break this week as I am blogging from my parent's home and recovering from a nasty bout of food poisoning.

This is part 2 of my critique of Teo You Yenn's This is what inequality looks like.

After completing the book, I became a lot more disappointed at this piece of work. The first half had vivid descriptions of inequality but the second half is a confusing mess. There were two chapters dedicated to the problem of the lack of dignity in the lower classes. One chapter, which I find really ridiculous, was about why the author refused to account for "race" in her research. It gave me the impression that she was passing the buck in order to pander to political correctness.

Anyway, let me illustrate why describing something well does not often lead to making better decisions.

There are a investment trainers and bloggers who take a qualitative approach to investing and this has done very well for them. They can describe a company's strategy and management very well. Even my friends in Maybank Kim Eng has invited me to listen to a few REIT managers to see if their REITs are good buys.

I always find this approach to investing difficult. Anyone can spin a tale and talk about good management is. Management can, in fact, be very sincere and can demonstrate why they are running the company well.

But a nice narrative alone cannot be an excuse to go long in a company stock.

Perhaps the stock is already overpriced.

How do you measure trustworthiness ?

Instead, I use rigorous quantitative backtesting to determine the portfolios I will build of the rest of the year. Some results of my backtesting may constitute financial porn, I will be starting with a portfolio that is purported to return 27% over the past 10 years. Every investment idea must be easily explainable and reversing the measurements can lead to negative returns, making double alpha market neutral portfolios a reality.

With this approach, I might still lose out to the touchier and feelier investment managers, but it's rigour lets me sleep at night.

I think the same applies to a sociologist's writings. Ethnographic research inevitably means that stories are anecdotal. Furthermore, I can tell from her writings that many social workers do not even agree with her and adopt a tough love policy to the people they are helping.

Teo You Yenn did not explain what is the price to pay to reduce inequality.

Who will suffer when we free the Child of Omelas from our basements ?

The true test will come when Singaporeans decide whether to open their wallets to overcome inequality in our society.

To many of us, that price would be too high.

Sunday, May 27, 2018

What Feminists Want


I made a promise to myself that I will not start criticising an author before I read her work.

This is what Inequality Looks Like by Teo You Yenn is an excellent piece of work which I thoroughly enjoyed.  But as a right-winged capitalist and patriarch, I would position her work in the same category as Thomas Piketty's Capital in the 21st Century. Capitalists do not read it with a desire to inequality - they read it so that they can be on the "correct" side of the rich-poor divide.

Instead of making me more sympathetic to the under-privileged, this piece of work has made me more anxious for my own children and for the next few years, I need to figure out how to entrench my children's position in Singapore society today because they will be a confused bunch - I believe that the 4G leadership is very open-minded to You Yenn's ideas which is why she has not been given the same criticism as other academics such as Donald Low or Thum Ping Tjin.

This book may be the defining work for Singapore over the next 50 years.

As I've only read half the book and, as usual, I still find that the book is long on problem definition but short on solutions. While sociologists excel at describing the problem, as my sociology scholar friend tells me that "we are doomed to praxis" -  Solutions in the real world must be better than the interventions that we already have today and should not introduce more problems.

Our social spending has already gone up since the 2011 elections. Welfare can have secondary effects as it kills innovation and the work ethic. Society can also destabilise if wealth transfers to the poor are seen by some as wealth transfers across racial boundaries - this was what caused the rise of Trump and the collapse of UMNO.

Some of the examples given by the book has really started to get me wondering at what really gets feminists off. So far, the examples in the first half of the book always concern women. One poignant example involves a mother of three called Nana who has a husband who can no longer support the family. But at the end of the story, Nana proceeds to get pregnant with her fourth child !

At what stage does personal responsibility come into the picture and society's obligations end ?

In essence, the plight of a lot of women concern their husbands. These are men who cannot focus on getting a job, who commit adultery,  and who stop supporting the household financially.

Why do women choose these flaky men when I have so many geeks pals who are nice, earning money but single ?

State intervention into these families are, in essence, a "put option" on bad husbands. Feminists want the government to get into the picture and raise their kids when their husbands refuse or are unable to do so.

This is, in essence, an appeal for portfolio insurance.

This is eminently unfair.

Women choose men based on the dictates of evolutionary psychology. Tall men with symmetrical features get a larger share of women in spite of lacking conscientiousness. Many aren't even agreeable.

This is why women marry dangerous men and jerks.

When these dangerous men leave their women to fend for themselves, feminists appeal to tax payers to support their kids.

Imagine my friends who are single, happily playing away in their Playstations in their apartments being asked by the State to subsidise children who do not belong to them. This income support comes in the form of higher GST, capital gains taxes or income taxes.

This is no different from asking husbands after a divorce to maintain children who do not share a DNA with them.

No one wants to be a cuck.

I hope Prof Teo would articulate what she really wants from society in the second half of the book.

I can't wait to read it.


Friday, May 25, 2018

Quantamental Investing and the Piotroski F-Score


I don't have much to talk about because I'll be spending the weekend in NLB to crank up more backtests for my next talk which is entitle "F.U. Money". I can't start my marketing blitz until I finalized my contents.

But here's a share on what I've been thinking about of late.

The latest buzzword being bandied around is Quantamental Investing and I did some Googling to find out how professionals do it. Right now, I can't figure out how this is anything new compared to what was done before so it is possible that some people invent a new buzzword to attract more investor money.

What I do know, and struggle with, is to find ways to incorporate the Piotroski F-Score into my  local stocks picks. Joseph Piotroski is an accounting professor who found stocks with low P/B generally fall into two categories - those that are cheap and will eventually go up in value and those that are cheap because its a failing business.

The Piotroski F-Score is designed as a scoring system to distinguish one from the other.

There are 9 tests in the F-Score which results in a score from 0-9. A low P/B stock is a good buy if it can have a F-score above 6.

Here are the nine tests :

  • Is the return of assets (ROA) for the last fiscal year positive?
  • Is the cash flow from operations for the last fiscal year positive?
  • Is the ROA for the last fiscal year better than the ROA for the fiscal year two years ago?
  • Is the cash flow from operations greater than the income after taxes for the last fiscal year?
  • Is the long term debt to assets ratios lower for last fiscal year when compared to that for the fiscal year two years ago?
  • Is the current  ratios higher for last fiscal year when compared to that for the fiscal year two years ago?
  • Is the average number of shares outstanding lower for last fiscal year when compared to that for the fiscal year two years ago?
  • Is the gross margin higher for last fiscal year when compared to that for the fiscal year two years ago?
  • Is the total asset turnover higher for last fiscal year when compared to that for the fiscal year two years ago.
The F-Score is a great way to learn how to read financial statements. More importantly it might be able to supercharge returns of a quantitative strategy involving value metrics like P/B ratio or Dividends yield. 

The problem is getting a tool that can calculate this score for all the counters in SGX. 

If any reader knows of a solution do let me know.


Tuesday, May 22, 2018

The Art of the Good Life #24 : The Spiral of Self-pity


Another short one,

There are three unproductive ways that we can deal with negative events.

a) Do nothing.
b) Complain
c) Engage in Self-Pity

The book misses out the fourth point :

d) Engage is self destruction

The trick is not to engage in any of these activites. The suggestion not to engage in self-pity comes about because there is no end to the injustice that your ancestors faced that led to your fate today.

I just want to say a few words about Millenials and personal finance.

In 2008 and 2009, our generation faced possibly one of the worst recessions ever. One effect of this is the rise of the Hipster. No, not the kind of hipster that sells rainbow-themed foods at the Geylang Bazaar ( Now that's really hopeless shit !) but the kind of ironic, frugal child of the Great Recession that is forced to work in the gig economy and avoid seriously engaging in the financial markets.

So this Millenial Generation was burned so badly by the markets, they eschewed Wall Street and missed out on the greatest bull market post-recession. But it gets worse - they invented a whole new asset class called the crypto-currency and dived into it without proper asset allocation and diversification.

Some became very rich but the majority are stuck with paper losses as they hold for dear life into financial oblivion.

For the folks suffering huge losses this quarter, try to avoid self-pity, just pick yourself up and start studying finance seriously.

At least, unlike me, you still have your youth.

Sunday, May 20, 2018

Feasibility of Bond Margin Financing


[ Feedback for this article is fast and furious !

Some concerns raised is whether investment grade bonds with a short duration can even be found in the markets ]


This has been a great week. The folks of Kim Eng held an open house and invited me to attend. The catered food was relatively good given that my exposure to free buffet is limited to what is available in SMU law school. They also gave me a pair of free movie tickets because I was such a special margin financing customer.

I'm just saying all this because I know they read this blog quite religiously.

Anyway, let's have a closer look at their bond margin financing facility.

Maybank Kim Eng has a fairly competitive rate to facilitate bond margin financing. I invite all readers to share with me what private bankers give them, but 2.28% is sweeter than my rates for REITs financing, but we have to live with the lower returns from bonds.

The framework I am using is the traditional use of the Kelly Criterion that blackjack players use to size their bets. The better the odds of winning, blackjack players will place bigger bets. I also employ a modification called the half-Kelly because gamblers generally half the output of the Kelly Criterion so as to err on the safe side when placing bets in a casino, this way they can survive longer.

Ok, so let's look at a typical deal the Maybank guys have suggested to me that night.

Suppose we have a bond with one year left to go. Let's assume that this is a bond issued by a local bank that returns 4% and is rated AA - it's a safe,conservative bet. As bonds are sold OTC, each bond position is a hefty $200,000. I also did some searching on Google and I found that in the worst case, a AA bond defaults with a percentage chance of 0.38% in a super bad year like 2008. This gives us a worst case scenario for a default. To simplify matters further, if a bond defaults, I assume  that you will lose everything even though the insolvency process might give you higher priority than shareholders.

So assuming that we have war-chest how much of it can we put into investing in this bond without leverage?

We apply the Kelly Criterion, or [b(p) - q] / b, where b is the odds on a success or 0.04, p is probability of success or 0.9962 and q=1-p or 0.0038. If this bond were a blackjack game, the Kelly Criterion will recommend that 90.12% of your war-chest can be placed on this bond. Sane gamblers use the half-Kelly and can invest 45.06% of their portfolio into a bet. At $200,000 for one position, you need to be almost half a millionaire to take this bet.

Now let's look at the Kim Eng deal that allows us to employ some leverage to buy these same bonds but at a cost of 2.28%. By leveraging 300%, you only need $66,667 to place a bet on one bond. There is, of course,  a 0.38% chance of utter ruin. Suppose we apply leverage, there is a 99.62% of winning (4%*3 - 2.28%*2) or 7.44%. This translate to odds of 0.0744. There is a corresponding chance of a disaster occurring with a probability of 0.0038 where we will lose 304.56% of our bet.

(Expect to lose everything when a bond defaults. Also you will owe the broker the money you borrowed from them as well. )

Put all the numbers into the Kelly Criterion,  the equation will allow us to bet [0.9962 x 0.0744 - 0.0038 x 3.0456] / 0.0744  or 84% of your war-chest. Using a half Kelly, this is a bet sized at about 42% of your war-chest.

What can we conclude from this exercise ?

a) A margin account for bonds allows a smaller retail investor to bet on bonds, something that is the province of the UHNW investor. The first case where there is no leverage, you will need about $400,000 to justify placing one bet on a bond. In the second case where you employ leverage, you only need ($66,667/0.42 ) or $160,000 to justify one position.

b) The equation covers credit defaults but most of the fear in our current market comes from interest rate risk. The smart money is betting that the Fed raise interest rates three times in 2018 and twice in 2019. If this prediction is wrong, there will be bigger shocks to bond prices. This is why leveraged bond bets should focus on bonds that will mature soon, like within 1 or 2 years of placing your bet.

c) Having bets with a size of $200,000 or $66,667 is still fairly large for a retail investor, so expect only quasi-affluent folks to be making use of this margin facility.

d) Unless you are a multi-millionaire, most of your positions will not allow you adequate diversification.

For now, I will be sticking with my REITs margin financing account which is doing ok. After it hits my ideal size and leverage ratio, I will not be ready for bond financing yet because I want to start working on a market neutral portfolio using CFDs which is something I hope to start doing in 2018.


Friday, May 18, 2018

People fail because they major in minor things.

The last article where I spoke about the complexity of Singapore life attracted some amount of constructive criticism from bloggers like La Papillon and Richard Ng, so I went back to the drawing board to see whether that idea can be reviewed or salvaged. 

In many cases, they are right, complex societies do not exist, only complicated people. And I think I tend to be more complicated than an ordinary Singaporean. In many matters, Singaporeans do have it easy compared to their international counterparts. Our tax code is simple and we do not spend too much effort trying to optimize our taxes unlike our friends in the US. 

One salvageable idea in that article is the advice that I give to readers not to major in minor things. I think this idea was invented by Jim Rohn and made famous by Anthony Robbins. 

According to Tony Robbins : People fail because they major in minor things.

Here's an example of what I did recently.

At this stage of my life, I don't want to be beholden to any employer. If I work for someone, I want the work to be interesting, rewarding or both. To do that, my finances must be able to sustain joblessness better than my 4 years of law school. Even better, I must be able to save more than most working folks even when I am jobless.

So I really wanted to optimize my expenses so I went through my broadband and mobile phone commitments. I went to a Starhub outlet and started to work with a salesperson to re-contract my phone and cable TV. The salesperson was actually quite nice and was willing to offer to me cheaper SIM only and no-frills cable TV plans. The total result of my effort was to shave off $50 from my telco expenses every month. Let's just say that in 2 years, this would have saved me $1,200.

Another hack I did was to buy a battery changing kit from a China vendor for my Oneplus 2 phone for about $20. With an extended battery life, I can now avoid buying a Google Pixel 2 and maybe even wait for the Google Pixel 3 to be launched. This can potentially save me another $1,300 over the next two years.

Net-net my micro-managing efforts yielded about $2,500 of savings over the next two years.

Now, suppose I move $200,000 of my portfolio from Tech stocks to my REITs margin account. I can push my dividend yields from 5% to 10%. This subtle change can net me an extra $10,000 in dividends every year. Of course, more effort would be required to do some research, but even if I miscalculate, an additional $5,000 with an improvement in the Sortino/Sharpe Ratio of my portfolio is quite a reasonable result.

As such, fooling around with Telco plans and optimizing some credit card benefits may be considered a minor thing compared to simple portfolio shift from Tech to Leveraged REITs.

But some decisions are even bigger than those involving your investment portfolios. Your decision to study for a degree will have a major impact on your total income you will make within your lifetime.

Choice of a degree affects your human capital. 

You can easily find a website and dig out statistics on starting salaries and employment rates of a degree program.

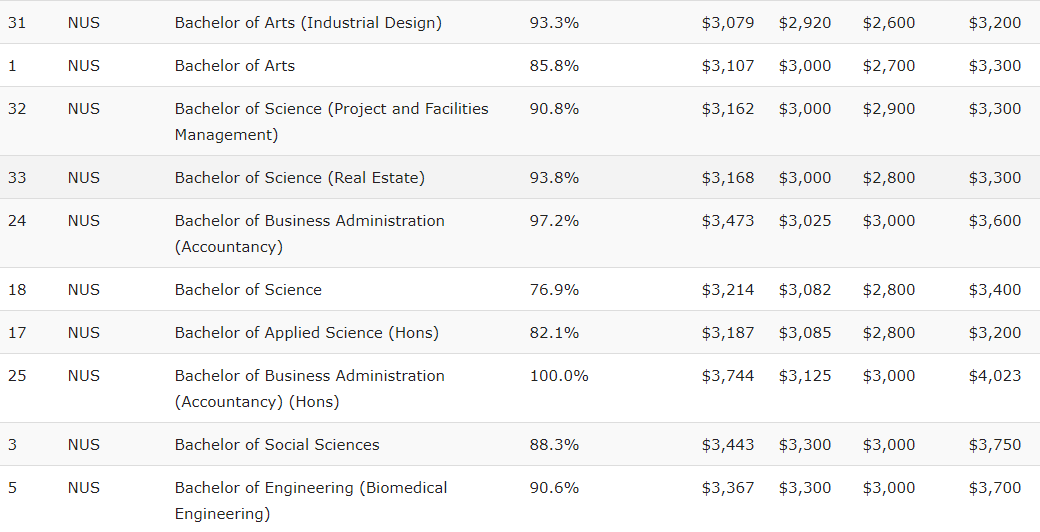
To stay politically correct, I have listed the worst NUS degrees you can apply for after your A level exams, omitting the truly abysmal numbers coming out from SIT. The third column from the right contains the median monthly income figures and the percentages are employment figures after 6 months of graduation.

In many cases, people do really major in minor things.

Enjoy !

Tuesday, May 15, 2018

The Art of the Good Life #23 : The "Good Death" Fallacy


Short post because I'm not feeling good ( sprained my back ) and it's been a long night.

The "Good Death" Fallacy is a mistake we make because we not give any weight to a duration of an event.

Consider Anna who was single, unmarried and had no children. She had good friends and enjoyed going on long holidays. At age 30, she suddenly died in a car accident.

Now consider Beth who was also single, unmarried and had no children. She had good friends and enjoyed going on long holidays. The last five years of her life was not as good as her first 30 years. At age 35, she suddenly died in a car accident.

When asked to determine who lived a better life, most surveyed participants said that Anna had a better life even though Beth lived 5 years longer.

Our mind is prone to over emphasize the peak in each event and how each event ended.

The duration does not matter so much.


Sunday, May 13, 2018

How hypergamy and rise of involuntary celibates affect our personal finances.


The recently Toronto attacks by a single man on women illustrates the danger of involuntary celibates to our modern society. If you have been following this blog, I write about about the rise of the useless caste - Video gamer males who do not participate in the labour and marriage markets. Involuntary celibates are a different archetype. Incels are angry men who are upset that they are being ignored by women or "Staceys" who prefer dating what incels label as jerks.

One of the root causes of involuntary celibacy among males is demographic policy. China is now ticking time-bomb because their rural areas are full of men who cannot find a spouse  thanks to the ago old practice of aborting female fetuses. A nation of millions of Incels is definitely not a safe place for our daughters.

But there is another reason for the rise of Incels.

Hypergamy is the act of marrying someone of a superior caste. The fact that women are generally hypergamous has been researched and generally supported by social science. The following paper rationalises this phenomenon - because women tend to invest much more heavily in offspring, women will tend towards marrying men with higher human capital and men want women with lower human capital because of men's desire to have legitimate children.

( My personal experiences being exposed to family law also seems to give me the impression that men with lower human capital marrying women with higher human capital will result in marriages of poorer quality. )

The effect of hypergamy on personal finances is largely ignored by investment gurus but it is far reaching and can impact your investments.

Face with a dearth of eligible women, men in China work punishing hours to own an apartment to attract a spouse pushing up real estate prices. Interestingly, many people still remains single. Chinese women who are highly-educated  and successful get dissed by society as sheng nu. At the other end of the spectrum, lowly educated rural men sometimes have to resort to kidnapping or sharing spouses.

Imagine our 4G leadership making a decision to re-introduce immigration to deal with our low fertility rate. The Chinese, being so used to high real estate prices, will definitely push up real estate prices in Singapore. This will occur without a corresponding increase in rentals creating price compression in local real estate markets. Wait... i think it's already happening today.

At a personal level, this means that I now see myself as a "corrupting influence" when I hang out with LLB interns.

To me, when a fresh male Law graduate starts a new career, the high starting salaries and career potential allows them some leeway to play a waiting game in the game of marriage. Their human capital is an appreciating asset and hypergamy guarantees that the harder they work on their cases, the more attractive they are as husband material. It's like playing blackjack and only committing the heavy bets when there are more 10s and Aces left in the shoe.

For the female Law graduate, the marriage game is much harder. The university is the last place where they will be surrounded by eligible men who are intellectually compatible with them. One bad move and they will miss out on the marriage markets.

I think this also answers my previous posts as to why we can't make RGS girls marry ITE guys.


Thursday, May 10, 2018

Why invoking Warren Buffett may be bad for the retail investor.


While Warren Buffett is over-represented in investment literature, the willingness of many gurus and trainers to channel him goes beyond belief. Invoking Warren Buffett in an investment lecture has almost become something akin to religious ritual. It creates instant credibility for the investment trainer even though in Singapore, he is not likely to be Warren Buffett.

( It's ridiculous right, it's like me quoting Xiaxue to get her readership figures.)

There are two instances in investment literature that show that such locally approximated "Warren Buffett" approaches might end up leading retail investors astray.

a) Quants have started figuring out the secret sauce of the Buffett technique

John Alberg and Michael Seckler in an article entitled Misunderstanding Buffett talks about how Berkshire Hathaway's returns can be replicated using factor models. A combination of value, quality, low beta and.... the liberal of leverage of up to 1.6x can allow a quantitative model to cover most of Buffett's returns.

Most of the time investment trainers tend to focus on the qualitative aspects of investment management like whether there is an investment moat or a sustainable competitive advantage or whether management is trustworthy. These are fluffy approaches towards investing which may cause the retail investors to lie to themselves and fall in love with a particular stock simply because too much time has already been spent analyzing it.

At this point I'd like to say that only Dr Wealth's Factor based approach seems to get the technique right with as little emotion as possible. ( While Alvin Chow is a friend, but he did not pay me to say this )

b) Berkshire actually runs three portfolios of which only two can be replicated by a retail investor.

 This second insight on Warren Buffett actually came from an autobiography by Ed Thorpe entitled A Man for all Markets whom I had a much closer affinity with because I'm primary a numbers guy, he is a mathematician and has beaten casinos in black jack and roulette before conquering the financial markets.

According to this book, the simplest way to look at Berkshire Hathaway is to see it as a collection  three portfolios. Only the first portfolio can be replicated well by a retail investor because it consists of publicly owned stocks. The second portfolio consists of GEICO/General Re - his various insurance businesses that allow him to create some kind of faux leverage through "insurance float", investing the premiums he earns that hasn't been paid out.  His third portfolio consists of stocks that simply are not publicly traded.like Wesco Financial and Clayton Homes.

Anyway, the next time you encounter a someone channeling Warren Buffett, you might want to read these two books and engage them in a spirited debate to see how their ideas hold up.


Tuesday, May 08, 2018

The Art of the Good Life #22 : Life Stories are Lies !


The world of RPGs is split between two broad player types. I belong to "Murderhobo" category. I create powerful PCs whose sole purpose is to kill monsters and spread mayhem in the gaming world. If the gamemaster gives me  a wish, I will often ask for a magic sword so that I can kill more monsters and spread more chaos in the campaign world. I like my RPGs to be chunky, mathematical and full of interesting loopholes. Characters possibly played by Murderhobo gamers include Saitama One Punch Man, Thanos, and Batman (Injustice).

The opposite of a "Murderhobo" is the "Storyteller". These assholes get into a game because they want to develop a narrative around their character. They wish to explore their inner world and how it interacts with the campaign.  These players value coherence of the campaign world and they hate murderhobos and the chaos we bring into the campaign. They like an RPG that is rich, descriptive and rule-lite Characters possibly played by Storyteller gamers include the Genos, Spider Man, and Batman (Dark Knight Returns).

As a dedicated "Murderhobo", of course I know that the "Storytellers" are wrong !

The narrative bias is my favorite cognitive bias because we are wired to love a great story. The ability to turn a set of disjointed facts is one of the key skills of a data scientist, litigator or a financial journalist.

Take for instance the recent rise of DBS stock which is currently the talk of the town. It's easy to spin a great story out of it. Perhaps bank stocks are rising because of rising interest rates and banks tend to become more profitable when interest rates are higher. But can this explain the recent fall in OCBC prices? You then go on to talk about DBS's fintech strategy which makes it part of the Fintech economy. As we discover more, we end up contradicting our story about DBS, you then go on to modify your story further to maintain its coherence. 

A good story has three elements that come in in the form of 3 Cs. It is "compact" or easily understood. It is "consistent" in that it does not contain an element that contradicts with itself. It is "causal" or formed by events that lead from one to another. Our human brain simply cannot accept facts as is and has evolved to turn any series of events into a story. This is the reason why we have superstition and religion - a story must be manufactured to explain a natural phenomenon.

Our inclination towards stories brings most of us to have some sort of life story for ourselves. It is some kind of lie we tell ourselves to make us seem more heroic than we appear to be.

This ultimately prevents ourselves from seeing ourselves realistically - multi-layered, paradoxical and incoherent.


Sunday, May 06, 2018

How would Thanos manage his personal finances ?


I'm quite sure most readers have watched Infinity War by now. In my opinion, the Mad Titan Thanos can be a great role model for folks trying to achieve financial independence. After all, who wouldn't want all the assholes in the workplace (along with some friends ) to disappear at the snap of your fingers ?

As it turns out, a person's journey to financial independence mirrors Thanos' attempt to collect all the Infinity Gems :

a) Mind Gem

The Mind Gem represents the skills you would need to understand how money works. For the rookie, I recommend reading the Richest Man in Babylon by George Clason. Then concepts of FIRE can be found in the works of Vicki Robin. After that you can try the more technical investing guides in the bookstore.

b) Power Gem

The power gem represents the ability to manage your energy. In personal finance it represents the ability to max out your life-energy exchange. A strong career and earnings signifies the ability to convert your life energy to money.

The power over life energy maxes out your earnings.

c) Space Gem

In the story, the space gem allows users to manipulate space and be at any location at the same time.

In personal finance, this represents the space between your earnings and your spending. The wider the space, the more savings you have. It is pointless having great life energy exchange when your excess cash is spent buying gadgets and useless stuff. This also explains why Thor is the God of Lighting, not the God of Hammers.

d) Time Gem

The time gem allows the manipulation of time and the ability to see into the past and the future. Now that you have adequate savings, power of time allows you to employ compounding to multiply your wealth. Compound interest is, after all, the eighth wonder of the world.

For astute fans, Dr Strange used the time gem to employ some of kind of Monte Carlo analysis to look into 1.4 million futures before deciding to conceded the time gem to Thanos.

e) Reality Gem

The reality gem allows everything in reality to be altered. To me, it means choosing the right reality of your investments. Picking a combination of stocks to you the best investment rewards.

Another aspect of financial independence that is not revealed in many books is that it is much better to test out your new lifestyle before adopting it. Otherwise how would you know that this new reality is the right one for you ?

f) Soul Gem

The Soul Gem is probably the gem that allows Thanos to snuff out 50% of the entire Marvel Cinematic Universe.

While it does not have a direct analogue in personal finance, we need to mindful of Nicholas Taleb's advice to always have Soul in the Game. To continue to engage meaningfully in the world around us, we need to retain some amount of soul or vulnerability in order for life to be meaningful.

I suspect that half of the universe is stuck in the Soul Gem with Gamora what's in the gem will be kep to undoing what the Mad Titan has done in the Infinity Wars.

So for readers who fantasise about making all the jerks and horrible people in the office disappear, it might be useful to ask yourself this question :

What would Thanos do ?


Tuesday, May 01, 2018

The Art of the Good Life #21 : The Memory Bank

This chapter gets you to consider the value of an experience as compared to the value of a memory.

Suppose you have a fantastic experience, like a conversation with God or your deity, but then after the experience you would forget about the experience completely - How much would you pay for that memory ? Now suppose you can remember the event for one day, one week or your entire lifetime. Would you value this experience with a higher premium ?

The author hypothesizes that most folks would not ascribe any value to an experience that cannot be remembered, and that more value will be attached to memories that can be recalled. According to the author, this is irrational as we are wired to only remember the peak experience and how most experiences end anyway. Furthermore,  memories become worthless once we are dead.

Next the author links this concept to idea of "being in the now" or mindfulness.

The part which I find of value is the idea that being focused on the now should not be misinterpreted as being not bothered about the future. Having plans for the future is compatible with the idea of being in the now. We can plan ahead, but once planning for the future is over, we can then refocus on the present moment.

I think this idea has merit.

On social media, there's viral story about a business man who meets a fisherman. The businessmen tries to convince the fishermen to up his game, scale his business, and be more ambitious in life but soon realizes that, in the end, the fisherman will end up being in the same position he is currently in.

This story is insidious and can mislead the reader into ignoring the bad things that may happen in the future.

If the fishermen tries to live his life in the moment and maintain status quo, unpredictable events can take him out of his comfort zone, and there may be no chance of recovery from catastrophic events. For example, a child falling ill may burden him with medical bills.  If the fishermen works hard to scale his business, he may accumulate more resources which can then be used by him or his family. While he might come back full circle much later in the future, he would have more resources to deal with calamities and may even leave a legacy for his children.

The moral of the story is that sometimes stories exist to pander to the weak and to defend lifestyle choices that lead to mediocre outcomes. 


Sunday, April 29, 2018

What is your Samuelson Number ?


Since we are in the topic of the Kelly Criterion and leveraged portfolios can be justified, let's about Samuelson numbers.

In the book Lifecycle Investing by Barry Nalebuff and Ian Ayres, one controversial concept they spoke about is called the Samuelson Number named after Paul Samuelson, the first American to win the Nobel Prize for Economics.

In this book, the book asks the following question to its readers :

If you would already be retired or financially independent today, how much worth of equities would you have. For some people, it might be, say,  $1,200,000 worth of equities.

Nalebuff and Ayres would then go on to suggest that a young graduate should employ 200% leverage to first accumulate $1,200,000 in equities and then pay off the amounts owed subsequently with investment returns and salary contributions. So a fresh graduate would start with a leverage of 200%, after reaching $1,200,000  the leverage would slowly start to drop until it becomes an unleveraged equity portfolio. Thereafter, investments beyond $1,200,000 will flow into the bond component of the portfolio.

I read Lifecycle Investing quite a while ago but I did not have the courage to put its ideas into practice. Over time, even Paul Samuelson began to question this approach because employing leverage meant skirting with the possibility of ruin.

I see modifying this approach using our low tax REITs regime as something feasible for a young Millenial investor today for several serious reasons :

a) We can now backtest a relatively powerful portfolio of REITs to return 10% which has a low standard deviation of around 13-15% and yield about 6.5%. This means that every $1 contributed into this leveraged pool can generate 10 cents in dividends every year. ( Currently achieved in my margin portfolio )

b) With 10% yields, a $2,000 passive monlthly income can be achieved with only $240,000. This allows the Millenial worker to cover his own expenses in a relatively short period of time in his early 30s.

c) Given how short STEM careers are because of technological disruption, this may be safer than trying to be loyal to an industry/company upon graduation because the need to keep  relearning your skills to stay ahead in the workforce or be relegated to the gig economy.

d) Once $240,000 is achieved, the worker will have two sources of income. His work is not over because he has to deleverage his portfolio to retire, but he will be in a way safer position than someone ho has to rely on his corporate job.

My challenge for the upcoming year is to use of my alchemical skills to combine the ideas of Vicki Robin, Barry Nalebuff, various Quantitative hedge fund investing approaches and a few other authors to create a new workshop that is mathematically tested to allow a new age knowledge worker to reach financial independence at the earliest time.

For now I have yet to complete this project because I have yet to begin crafting a backtest pure equity portfolio.

But in the meantime, it will be great to start thinking about your own Samuelson number.


Thursday, April 26, 2018

Applying the Kelly Criterion as a middle ground between a War-Chest and a Leveraged Portfolio.


This week has been really rough for tech manufacturing and income stocks. But what really saved my portfolio was my margin account which held up while the rest of my portfolio got battered. I really look forward to creating another back-tested equity portfolio in time before my talk.

Anyway, one possible middle ground between the war-chest and the leveraged portfolio is the Kelly Criterion. If you have heard about the casino antics of Ed Thorpe, you will know that he was one of the first to come up with a practical approach towards making bets using the Kelly Formula.

You can find the derivation of the formula for the Kelly Criterion for stocks on this link.

For most of us, we just need to know that the proportion of our war-chest to devote to an investment is equal to ( stock return - risk free rate ) / ( standard deviation of the stock ^ 2 ).

So if perform a back test and find that the STI ETF has provided returns of 3.5% with the risk free rate with a standard deviation of 19%.  We can also derive the risk free rate by using the 10 year local bond current yield of 1.8%.

The Kelly Formula yields (0.035 - 0.018) / (0.19)^2 or 47%.

So you should put 47% of your war-chest into the STI ETF.

Suppose you conduct a back-test and figure out a way to create a REIT portfolio that returns 10% with a standard deviation of 13%, let's see what happens instead when we use the Kelly Formula.

The Kelly Formula in this case yields (0.1 - 0.018) / (0.13)^2 or 485%.

A lot of gamblers suggest using this thing called a Half-Kelly so that your position sizing becomes even more conservative. So even if we take half of 485%, 200% leverage is not as insane as some bloggers make out to be.

As a person who only uses 200% for less than a quarter of my total net worth, I really do not suggest that you use an equation to position size a margin account.

What I am saying is that mathematics may be able to reconcile the differences between a war chest investor and a margin account investor.

Sometimes both can be right.

Tuesday, April 24, 2018

The Art of the Good Life #20 : Your Two Selves


[ My pal 15 Hour Work Week has also started a regular series on this Rolf Dobelli book as well ! I read his blog here because he has a different take on this book and I read it to revise its concepts. ]

You have two selves.

The first self is the experiencing self. This is part of the consciousness that is in the present, taking in all sensory perceptions real-time. This part of the self has to sift through millions of data points just to retain a few of it for storage in long term memory.

Which leads us to the concept of the second self also known as the remembering self. The remembering self  gathers, arranges and evaluates all the data captured by the experiencing self.

These two selves evaluate events differently. In fact the remembering self tends to over-emphasize peak events and the also the things which occur right at the end of the event itself. This is the reason why some people who suffer during BMT tend to see it more positively in retrospect.

This idea may explain the behavior of the folks who reach Financial Independence.

It does not matter how long it takes for  someone to reach financial independence. In retrospect, the triumphs in a person's career will determine how he assesses his journey to reach cross-over point, where passive income exceeds expense.

This further means that, without an extremely unpleasant event that actually ends a person's career, folks will generally not voluntarily end a career journey after reaching financial independence. We often get out because we get retrenched or meet very toxic people in the workplace.

We can extrapolate some useful insights from this realization beyond the Rolf Dobelli book.

Those who first reach Financial Independence and then pull the trigger to Retire Early will always tend towards Introversion. This is because the workplace will always be a place of over-stimulation. Endless meetings, presentations and chats next to the water cooler.

Which leads to a deeper realization.

When you read the articles of a financial blogger, invariably you will encounter someone who is heavily biased towards advising readers on what best to do with their money and life and that this advice would actually work against extroverts.

This is where we see the extrovert minority struggle to understand why people are so eager to retire even within this community.

I don't see a problem for extroverts trying to reach financial independence. The trick is to get there first, and then ask yourself how can this financial independence be used to make a bigger dent in the Universe.

Failing that, more money may just mean bigger parties and louder music speakers.

Sunday, April 22, 2018

Cryptocurrencies are DOOMED !


Given that cryptocurrencies are going through a minor recovery of sorts, it is time to have an update on cryptocurrency investing.

April 2018 is a very fortunate month for folks who are interested in this asset class. This is because Barclays Bank has devoted most of their Equity Gilt Study 2018 report to technological disruption and cryptocurrencies. While I do not have the actual report, the Economist has summarised what it had to say about the state of cryptocurrency investment world.

The basic gist of the study is that cryptocurrencies have peaked. There will no longer be another upside like what the luckier millennial investors have just enjoyed. The reality that this investment class does not produce a dividend is now sinking in.

Cryptocurrencies also face four challenges :

a) There is a lack of trust in cryptocurrencies. 

Generally speaking, people trust currencies backed by government.

b) Cryptocurrencies lack sovereignty. 

Governments and businesses hate it because there is potential for tax avoidance.

c) Third is privacy. 

Once you lose your private key, every transaction made on the wallet will be revealed.

d) Irreversibility. 

Finally blockchain transactions are hard to reverse.

Where cryptocurrencies remain relevant are in societies where trust is minimal or already lost. It is not difficult to imagine that cryptocurrencies will be quite useful in  a failed state like Venezuela.

How Barclay's bank concluded that the peak is over for cryptocurrencies is super interesting because they got their whiz kids to model the euphoria like an infectious disease. There is a ridiculous ramp up of prices at first but eventually the disease fizzles out as a large part of the population is immune to it. Once prices falls, investors lose hope and sell. Soon prices fizzles out, just like the way a fever breaks.

I really want to get a copy of the report because the approach to model cryptocurrency as a disease outbreak is really cool and amazing and can be reapplied for other asset bubbles.

For now I have concentrated my cryptocurrencies in my Coinbase account and will be liquidating it soon since Coinbase will no longer work with XFERS on 15 May 2018.

If I just retrieve my cash into my margin account, I would have enough to sustain my mortgage payments, effectively attaining my biggest resolution I have set for myself this year.

( If a reader is a a private wealth client of Barclay's bank and access to the document, I'd be most grateful if somehow you can send me a link to a PDF copy)


Thursday, April 19, 2018

You can choose your reality.


When I was single, I thought of wanting to join SDU, so I consulted an engineering classmate who frequently attended these SDU events, hoping that he can give me some  dating advice. I was a desperado and wanted to know what were my chances of finding a significant other when I joined these events.

My friend understood my 20-something self very well so he wanted me to be less of a jerk than already was then. I remember we were riding on the north-south line and he told me that in order to succeed in SDU, I must get used to having dates with average-looking women. So he pointed to me three women of my age sitting opposite us in the MRT.

The first woman was really plain and I would not have noticed her even if she was standing in front of me. The second woman was actually quite a turn off because she had a lot of acne on her face. I can't remember what turned me off the third woman, it might have been her weight. What I do remember was jokingly telling my friend that if I am left with these girls, my family line would be essentially over and I would choose eternal loneliness over a domesticated life.

What is the moral of this ridiculous anecdote ?

Organizations and salespeople exists to create a new reality for you.

SDU's approach towards getting more graduates to date is to bombard them continuously with average looking women and men with average charm so that expectations can be lowered and an eventual match takes place.

They are the in the business of lowering your expectations.

As investors in the 1990s, unit trusts were the rage. In my first book, I wrote about expense ratios and management fees. In those days, I invested in unit trusts like the Templeton Global Equity Fund which could charge over 2.75% in annual fees. Even if equities gave 9%, I would make barely 6%. Dollar cost averaging was the hot new thing 20 years ago.

That was the reality then.

The insurance industry is worse. Agents routinely sell their products as being better than bank deposit rates.

While the situation is much better, we need to careful about the products sold in the markets today, ETFs are highly advantageous compared to actively managed funds but we are seeing very unexciting returns from the STI ETF at around 3.5% last year when simply buying an equal-weighted basket of STI components can give a 1.5% boost to your returns.

So in essence, in the world of investments, you can create your reality.

When I started back-testing a portfolio on Bloomberg, the world of double digit returns with a lower semi-variance suddenly opened up to me. When I started employing leverage, having an expanding portfolio without the need for a day job became a new reality to me. So much so that there are projects that I am eagerly looking forward to doing by the end of this year involving the shorting of stocks.

New realities can also backfire. Cryptocurrency prices can double in a short span of a week. Now we could be seeing a nasty backlash in 2018.

The trick is to stick to the fundamentals like diversification and risk-position-sizing to ensure that there is a way out when the reality changes.

Monday, April 16, 2018

The Art of the Good Life #19 : The Smaller Meaning of Life

The larger meaning of life are questions relating to what you re are and how you fit in into the Grand Scheme of the Universe. These are questions that are hard to answer and require a lot of introspection.

The smaller meaning of life is a lot easier to attain because all you need is to understand your goals and ambitions.

The book talks about research done on children. Those kids who consider money as something indispensable had a higher income later in life and are generally happier than those who did not value money as much. Of course, those who valued money but did not achieve material success later in life are the most miserable of them all.

The surface advice from the book is that goals matter. Popular self-help supports the idea of SMART goals.

Scott Adams takes goals one step further and asks the questions of what kinds of personal systems can be built towards attaining personal success as opposed to following simply goals. Habits and rituals are more effective than goals.

So I guess a more complete picture is to first know what your ambition is followed by your goals, and then to find out how to build a system or series of habits to achieve your ambitions.

My goal right now is to offset my mortgage with my margin account. To do that, I have to save about $4,000 a month on an allowance of $800. This means really skimping on on the use of my dividends every quarter.

To do that, I developed two systems :

a) Fish soup once a day. As Maxwell road hawker center soup serves fish soup that is well above average, I get a healthy meal that keeps my blood sugar low at a mere $6 a day. Somehow good healthy diets can drive overall savings since I spend less time at restaurants.

b) Book moratorium on the poor dividend months. Every January, April, July and October, I stop buying e-books and RPGs so that I can use the library more and select only those that I can read in that quarter.

As we speak, my margin account is getting close to $480,000 in size which generates about $24,000 a year. This is not a small achievement as I had no earned income building up this margin account and I was able to  keep my core portfolio generating income that  I can feed my entire family with.  As my margin account is full of higher quality REITs, yield accretive moves should be able to tip me over to be able to offset mortgage payments hopefully by October 2018.


Saturday, April 14, 2018

Managing your Attentional Capital or Focus


Today I went over to Starhub to re-contract my mobile phone into a SIM only contract. By doing that I resolve a painful problem I have been facing since I started work in a law firm - I have two devices that employ mobile data that I bring to work, a mobile phone and a tablet. For months, I have been exceeding my data usage by 4Gb and have been spending $200+ on telco expenses every month. So today was the expiration of my contract so I rushed over to switch to a SIM only plan with 16Gb of data allowance.

The conversation was amusing. The sales executive tried to bait me by telling me that I am losing a $100 phone voucher when I refused to get a new phone. I told him that because I used so many extra Gigs of data, I am a good customer of Starhub and I need to stop being a good customer starting today. He then said that I will lose my double data allowance once a year is up. I then told him that by then, I may choose a new Telco by then as there would be four players in Singapore.

I wanted to tell him to stop up-selling so I told him that I'm a Starhub shareholder and I appreciate his up-selling efforts but I'm minimising what I pay to his company to him moving forward.

The conversation then veered into investing and we started to talk about Starhub dividends. I told him that he was stupid for not investing in Starhub because of the 6% yields he's likely to get and that if there is a drop in dividends he would be the first to know because he would be facing more customers like me who are either bailing out or cancelling a plan. The rest of conversation is about how to open a brokerage account and get started to make more money from his company.

That look on his face when I told him that his company pays me better than a bank deposit was priceless.

Even more amusing was that I ended up selling to him.

Ok... This is a pointless story.... I am rambling... All I wanted to say on this blog post is that we need to conserve our attentional capital or focus.

Singaporeans are lucky compared to Europeans and Americans in that very little attention needs to be paid on taxes because out taxes are quite low. Beyond that, life is pretty complicated on this island.

Here are some examples :

a) We spend too much of our time thinking about CPF which is a confusing monster of a scheme because it covers retirement, education and housing.

b) Property ownership takes up too much of our time as well because the asset enhancement depends on our attitude to foreigners and how we prioritise the needs of home owners versus home buyers. I keep getting into Whatsapp chats where people just speculate about property movements and talk about stupid condo launches. But no one ever talks about tolerance of foreign labor which will drive prices moving forward.

c) We have to consider our educational needs - you can't buy a private degree anymore in Singapore because HR departments will hardly consider the degree worth the paper it is printed on. Replacing this is the possibility of developing skills using Skills Future Credits.

d) There are also other endless distractions that we need to think about : telco expenses, insurance expenses and credit card rewards.

If your personal finances rely on so many moving parts, it simply means that smarter and more conscientious citizens will have an edge in society. They simply can take advantage of more schemes to generate more revenues and savings. Just now, I was teaching my single friends about the Entertainer App, something I picked up from Budget babe's talk last year.

For the folks who are not that smart, you would have to prioritise what area to focus on and stop majoring in minor things. This is why I wanted to stop paying for a mobile phone plan and separate my data plan from the gadgets peddled by telcos. For that same reason, I absorbed the risk of floating rates for my mortgage so that I don't have to keep monitoring which fixed rate plans are the most advantageous ones out there. I have been using the same DBS VISA Classic card since I started work and have never asked for a fee waiver in my life. All my card rewards go into paying the annual fee and Popular vouchers.

As life becomes more complicated, the one rule to follow is to simply follow the money.

If the STI ETF provides a return of 3.5% and you backtested an equal weighted portfolio of STI components give out 5%, a $100,000 shift in your portfolio nets you an extra $1,500 a year. If you can backtest a REIT Strategy that gives 10%, then you can earn an extra $6,500.

That's $6,500 every year after you tilt $100,000 away from the STI ETF.

For those starting out, a well executed job switch may net a 20% increment.

No amount of optimisation of your telco bill or credit card rewards can generate extra revenues like that.