Thursday, April 12, 2018

Hacking your own Millionaire Mindset.

I think that we may have gone too far telling everyone what a Millionaire Mindset is not. The Millionaire Mindset is not about affirmations. Generating wealth is also not about sharing the quotable quotes of billionaires - although running a business selling motivational posters might actually work.

Now it's time for me to propose a generalized procedure for someone to develop a genuine Millionaire Mindset that puts him within a reasonable striking distance of landing a million bucks. Now in order for this to work, you need to read a lot. If you cannot accept this rule, then my approach will not work for you.

I propose that the Millionaire Mindset is hidden behind three books.

1. The Millionaire Next Door by Thomas Stanley


Nothing cuts through all that motivational crap like hardcore academic research. The Millionaire Next Door is a little dated by now but it shows some of the common traits and habit of everyday millionaires from the perspective of a sociologist. This is where most of the fundamental ideas of frugal living and avoiding flashy consumption come from.

I consider this the first book to read to develop this Mindset.

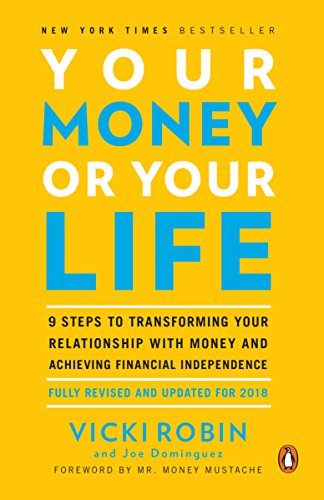
2. Your Money or Your Life by Vicki Robin


I read the earlier version of this book which was co-authored with Joe Dominguez. It's not an easy read but it's a textbook on FIRE and may contain humanity's first attempt to characterize financial independence as a cross-over point between basic expenses and investment income.

This is a crucial second book because financial independence is the bridge between survival and attaining millionaire status. It's like castling in a chess game to build up a defensive position early so that you can checkmate your opponent later.

Achieving financial independence allows you to farm your entire income into your portfolio allowing millionaire status to be achieved a short while later.

3. Seeking Wisdom : From Darwin to Munger by Peter Bevelin


The final book in this series is really about mindsets. I think that there is a certain way to think that makes you a better investor, worker or entrepreneur.

I'm in the middle of this book and most bloggers have not featured this book yet because it is quite unique as it unifies some key ideas in  Evolutionary Psychology, Behavioral Finance and some of Munger's ideas on Mental Models into a very interesting read. I think this book should supplant Thinking Fast, Thinking slow by Daniel Kahneman and Amos Tversky in a financial blogger's bookshelf because it much more accessible to lay persons.

Of course, developing a Millionaire Mindset may not make you a millionaire immediately.

But this is certainly a better alternative than the wishful thinking recommended by the folks who wrote The Secret.

Tuesday, April 10, 2018

The Art of the Good Life #18 : The "End of History" Illusion


I said recently on social media that an intelligent woman is like a magical sword. If you are not capable enough as a guy to wield this weapon, you can get yourself hurt really really badly.

A very intelligent and capable lady once bragged to me that her husband/boyfriend is a lucky guy because she is smart enough to say the right things to motivate him so that he can become very successful in life. She will push him to become an alpha male, a leader of men that commands respect.

Someone suitable enough for a daughter of a better age.

But as smart as she is, here's something that she does not know about us men.

It's hard to change us.

Changes happen as we interact with the environment. We change only when we are internally motivated to do so. A lot of tragedies in families arises from the desire of the wife to change the husband. A typical tragedy always involve marrying a man-child and expecting him to become a responsible dad overnight. I think you have better luck hoping for a rebound in crypto-currency prices.

While it is hard to change someone, we are always changing - just not in ways that some ambitious or highly intelligent women would find desirable. The rate of change is constant throughout our lives. A hard charging executive might become a lazy has-been after reaching his 40s. Even I changed from a gainfully employed  technology professional to a woefully underemployed legal professional.

Thus the HR adage that companies "hire for attitude but train for skill" is a wise move.

[ Kudos to this intelligent lady I spoke of. She become a highly successful executive and married a truck driver. ]


Sunday, April 08, 2018

Personal Update

This might be a great time to just give a personal update.

a) Training Contract

At this stage, I've reached half-time for my training contract. I've learnt quite a bit of from the past 3 months although for the sake of confidentiality, it is best that I do not provide too many details about my work. Most of the learnings I have derived from my work is how to manage our lives so as to avoid legal problems much later on. Sometime the most innocent moves like treating some of your children better than the others can have huge implications decades later.

Right now, I am slowly ramping up my job search in all the sectors what I can competently work in, targeting the jobs that are out of my league at the moment to see if I can get an interview. This includes the IT sector. I have not much luck so far and even managed to get a rejection letter from a headhunter.

I doubt things would look this easy looking forward in my 40s but I need to ramp up my job hunting efforts next week.

b) Personal Finances

There is a certain magic about working in a job that pays a 3-figure allowance every month. Because I try to eat healthily, I tend limit myself to Fish Bee Hoon meals at Maxwell hawker centre everyday.  l also avoid anything that may put me in a carb coma at 4pm during a workday.

The results from a savings perspective is quite astounding.

I managed to save $4000 every month for Q12018 because I have fewer avenues for spending my money. Reducing this by my home mortgage payments, $1800 is still pretty good and more than many median income families.

c) Financial markets

The maths in the past paragraph does not really check out if you are a new reader and do not really understand my personal situation, but most of this can be made possible because of my new margin account where I leverage high quality REIT that yield 6.5% to yield 10%. This new source of yields complements my old portfolio that yields closer to $5000 - $6,000 a month these days because it has more Tech counters these days.

I think 2018 would have been much better if not for the trade war started by Donald Trump. Over the short term, my portfolio has been experiencing a lot of fluctuation for the past 2 weeks. Medium term, I am cautiously optimistic as Singapore exports may even benefit from the situation.

Like most market watchers, I'm closely watching MAS's next currency moves which may lead to the tightening of the SGD. This can possibly lower SIBOR and make it cheaper to finance our mortgages and make our property more valuable this year. The downside is that our exports can become less competitive.

d) Cryptocurrency markets might be killed in May for many Singaporean investors

Last year, I was cursing myself for not putting enough into cryptocurrency. This year, I'm glad it's only small part of my gambling money.

News of Coinbase stopping Xfers transfers is really bad news and it might be an end game for many crypto investors in Singapore. I'm waiting for alternatives to be proposed by the blogosphere.

For the millenials who keep bragging about their crypto efforts, I wonder how they are doing right now.

e) Book moratorium

On January 2018, I decided to hold a 1 month moratorium where I was disallowed to buy any books so as to generate more savings to ramp up my margin account. It has been rather successful and I have decided to do this for all my low dividend months of April, July and October.

I still have plenty of books to read including a biography of Ed Thorpe and Jacob Fugger. I will feature these reads on this blog at a later time.

f) Leisure

Managing a blog, working on a finance workshop and family means that I have no means of leisure. Maybe I can start gaming a bit in July 2018 when I will give myself a break after my training contract.

Saturday, April 07, 2018

Is finance gendered ?


Let's imagine a finance seminar for men ( and men only ) that is relevant to you regardless of whether you are an alpha male or a BBFA.

a) It will focus on lifelong learning and address the issue why boys are not doing too well in school compared to women.
b) It will talk about earnings of blue-collar men who are not getting increments based on inflation rates.
c) It will discuss strategies of saving money by bingeing on Netflix, cutting cable and playing computer games all day. Even discuss the most optimal car to own.
d) It will focus on saving more money by eliminating male-dominated vices like smoking or drinking.
e) It will talk about investing on passive income to offset computing gaming expenses and Geylang escapades.
f) It will address men's shorter life-spans and adjust a mix of annuities and term life accordingly.
g) It will consider the prevalence of divorce and update the men on how our courts will rule on matrimonial asset division, custody of children and maintenance of spouse.
h) The tone will be humorous and filled with hours of filthy jokes along with good advice on money management.
i) Goody bags will be filled with condoms, Viagra, Astons vouchers and Tiger beer.

The question is why does such a seminar not exist ?

I think it is because people might find it absurd.

But once we flip that idea for women, this is common business practice and quite a few start-ups are doing quite alright providing financial education for women.

I think investing is not like writing novels. You can write a novel like 50 Shades of Grey that appeal to mainly to women. The financial markets are fairly consistent to male or female investors. While it can be argued that women tend to trade less and are more conservative in outlook, I know of many men who invest like women ( and do quite well for that matter ). Of course, there are also women who buy shit-coins like the most foolish of millenial males.

In my opinion, finance is different beast. SPH does not pay a different dividend to a man as opposed to a woman. One of my most admired financial journalists is Teh Hooi Ling and I try my level best to adapt to her quantitative investment style towards portfolio building.

The decision to segment the population to cater specifically to women is a business decision and not really based on a superior investing model that someone only works when executed by a woman.

It would be good to hear from women why they need a "safe space" to discuss money matters.

It seems like a gender neutral issue to me.


Tuesday, April 03, 2018

The Art of the Good Life #17 : The prison of a good reputation.


This chapter begins by asking the question of who would you rather be :

a) You are the best lover in the world but everyone thinks that you're the worst lover in the world.
b) You are the worst lover in the world but everyone thinks that you're the best lover in the world.

Most folks would choose (b).

The chapter however goes on to show that being obsessed with how people see you can be bad for your mental health. After all, all thanks to social media, we have all become managers of our personal brand. I am always performing a Google search on my own name and measuring the number of eye-balls that this blog attracts. Articles on back-testing and correlations would attract me about 300-400 eyeballs a day but brutal truths about private degree holders will net me thousands of eyeballs over the next 24 hours.

Would switching to internal measurements make you better off ?

It will certainly make you more comfortable, but I know of too many people who set such a low bar for themselves, so much so that they don't achieve very much when they hit their middle age. Furthermore, the book admits that our ancestors needed to maintain good reputation before they could survive as part of a tribe.

I guess this is why financial independence is so attractive to many readers with introverts taking a particular idea to leaving the rat race.

The only measurement that matters is your passive income. After it exceeds your basic living expenses, you can start living the introvert's dream of leaving the workplace and isolating yourself in your little cubbyhole without a care of what the whole world thinks about you.

But for me, there is a slight problem...

I am an extrovert.

My financial independence gives me more ways to engage with readers and fans through talks and seminars.

Perhaps a simpler question would be to choose between :

a) You are the worst investor in the world but everyone thinks that you are the best investor in the world.
b) You are the best investor in the world but everyone thinks that you are the worst investor in the world.

(b) makes you a Warren Buffett.
(a) Makes you a hedge fund manager for an LTCM.


Saturday, March 31, 2018

A Millionaire mindset is a Low SES mindset !


The genesis of this post came from an anecdote from a friend who attended a financial talk over a decade ago. This financial talk was conducted by a famous options trading guru ( who has since had a very disappointing day in court and is no longer giving talks on options trading today ). Halfway during the talk, my friend was either so bored or so offended by the presentation that he abruptly stood up along with his friends to leave the lecture hall and the speaker then pointed out to my friend's group and proclaimed that " These are the people who do not have the mindset to become millionaires."

There is something which I think has to be said about the mindset of the millionaire as possibly espoused by these trainer gurus, MLM or insurance salesmen types. These ideas are largely derivatives of the writings of Rhonda Bynes in  The Secret or some other mindset changing work of authors like Harv T Eker which in turn are derived from authors in the 1980s who talk about programming your mind like a computer or Psycho-Cybernetics.

If you have enough friends over the years who subscribe in wishful thinking and how a person's mindset can be tweaked towards earning more money, you will realise that somehow a lot of more of these people also tend to fail rather than to become actual millionaires. Perhaps they blew their savings on a nice car because frugality is for "middle class" folks. Or perhaps they had to "fake it until they made it".

Which is why I came to this realisation :

The Mindset of Millionaire is the Mindset of the Bankrupt !

Because the Millionaire takes greater risks than most people,  so they tend to end up with greater wealth. But those who take bigger risks also have a larger probability financial ruin. So the same mindset creates more bankrupts.

This is something we need to be cognisant of.

Compare this with mindset that the Financial Independence community espouses.

In our community, we rarely use words like "Millionaire" because it triggers a lot of lay people and hijacks their amygdala. People stop being rational when millions of dollars are involved in a conversation.

Instead we talk about earning, saving and investing your way towards financial independence where wealth targets are largely a function of your daily expenses. A single man who invests well can comfortably slow down when he has $400,000 invested in high yielding stocks and REITs. A family may need $1.2M.

Here's the deeply counter-intuitive idea : Even a millionaire who supports our approach towards Financial Independence should be well aware of how low a millionaire's real social economic status is.

Suppose your family has $1 milllion dollars invested in a popular SREIT ETF, this translates to perhaps $55,000 a year at 5.5% yield or $40,000 if you agree to a safe 4% withdrawal rate. This is well below the median income of a Singapore household ( which is around $100,000 these days ). A millionaire (who lacks an earned income) has to live below the means of the median income family.

This means that a millionaire household has to adopt the lifestyle well below that of a HBD dwelling family to sustain their well-being over time.

This is why the FI community supports the notion of frugality above all other concepts in personal finance.


Wednesday, March 28, 2018

The Art of the Good Life #16 : Tyranny of a calling


"Few people are as unhappy as those with a talent no one cares about." - John Gray.

The lesson in this chapter is that chasing after a calling is a recipe for a miserable life. Having an over-inflated expectation that we need a particular vocation that stems from something deep inside is a loser's game.

The chapter provides the example of writer John Kennedy Toole, who had his conviction about being a successful writer shaken to the core after numerous rejections from major publishers,  committed suicide by carbon monoxide poisoning. After his death, A Confederacy of Dunces sold millions of copies and was awarded the Pulitzer Prize.

Amazingly, the chapter neglects to offer an alternative to the tyranny of a calling which is provided amply by the works of Vicki Robin in her masterpiece Your Money or Your Life.

It is eminently more practical to view your vocation as a means of exchanging life energy for money.

No matter what we do, we are in essence, trading time for money.

Consider the efficiency of your use of your life energy by figuring out a number with the numerator being your salary minus all expenses associated with your job (such as transport or the cost of looking the part). The denominator consists of the time spent in the office every month plus expenditures of time outside office hours networking to get more business or commuting to the workplace.

If my fellow trainees perform the calculation, some, like myself,  may find that they have a lower efficiency than most domestic workers in Singapore.

Others, such as the financially independent crowd who have a value investing or dividends based focus, will find that they are more efficient with their life energy than members of the Cabinet.


Friday, March 23, 2018

On the hypocrisy surrounding War-chests and Leverage investing


Not everyone is a big fan of leverage investing using a margin the account. It is probably not coincidental that some of these detractors of margin financing also tend to employ a war-chest when describing their investing strategy.

In my opinion, margin investing and the employment of a war-chest are two extremes in investing.

Much like Law and Chaos in Michael Moorcock fantasy novels.

When you invest using leverage, you are trying to magnify your returns by borrowing money. If the cost of borrowing runs below the rate of return of the unleveraged portfolio, you are likely to succeed in getting better returns provided if the underlying investments generate positive returns. The problem of a leveraged portfolio is that there is a chance of complete and utter ruin, which to me is the odds of a margin call. In essence, you are trying to get higher expected return by flirting with the odds of ruin.

A war-chest is the opposite of a margin account. You hold a portion of your portfolio in cash so you are not subject to market risk at all. The downside is that if you calculate your rate of return, your cash component of the portfolio returns 0%, worse than buying government bonds.  You are trying to securing your portfolio from losses by lowering your expected returns.

Both camps harbor fantasies on investing outcomes.

Leverage investors harbor fantasies that they would be able to avoid ruin but the odds of ruin can be estimated if you use the right statistical model. I consider 1 in 40 odds to be generally acceptable in my margin account if I can extract 10% yields for my trouble.

War-chest investors also harbor fantasies. There is this belief that the investor can time the markets to produce returns that can overcome the deficiencies of cash drag that have been adopted by the investor. Right up till today, I have yet to see a modelling attempt to justify market timing using a war chest. All I see is a lot of chest thumping and vanity displays of personal results, very often in un-diversified portfolio which does not help readers who want to replicated the strategy.

As of now, I'm still waiting to back-test a model that incorporates market timing with a war-chest. I simply do not see leverage investing and having war-chest as something that mutually exclusive to each other.

If a good marketing timing strategy exists, a savvy investor can hold his portfolio in cash and make tactical leveraged bets in a margin account. 


Wednesday, March 21, 2018

The Art of the Good Life #15 : The Secret of Persistence


Old age and treachery will always overcome youth and speed.

This chapter is about persistence.

The secret to success is about taking steps to sustain your smaller successes and have them compound over time. This is why Warren Buffett is always used as some paragon of compound interest in many personal development books even though we ignored his earlier tactic of buying up cheap companies and forcing management to unlock value by board control. There is some quantitative backing to Warren's slow and steady form of wealth accumulation, the Sharpe ratio of Berkshire Hathaway was known to be between 0.7-0.8 when hedge fund strategists are using strategists that go north of 1.

The other example which I enjoy is the concept of a long-seller. Books like 50 Shades of Grey are bestsellers, but they may not persist over time. Lord of the Rings, however, and Jin Yong's works will be sold in bookstores so long as there are still bookstores left in this world.

How to come up with something that persists?

The general guideline is to pace your work and not work too hard to the point whereby you burn out. Personally, I think you should aim for small successes and then scale them into bigger ones without tiring yourselves.

This is why looking for dividend yields work in investing. No doubt high-yield strategies tend to under-perform quantitative strategies involving FCF/Price and EV/EBITDA, but seeing dividends trickle into your bank account is relaxing and therapeutic, and very often you become motivated to save more for the future. Eventually you may be able to sustain this form of investment whereas someone with a more formidable formula would have sold out in the next market recovery. 

Nicholas Taleb elegantly expresses the power of persistence by his concept of the Lindy effect. If a literary work is popular for one century, the rule of thumb is that it should be popular for another hundred years.


Sunday, March 18, 2018

Thoughts on yesterday's Computation Law and Blockchain Event


There is nothing that a seasoned IT professional despises more than a lawyer who obstructs his projects in the corporate world. I should know, because I hated these corporate lawyers so much, I became one of them just to figure out how to prevent them from cock-blocking me at work.

After a week of training, the last thing most trainees want to do was to attend a full-day seminar with other legal professionals but this event is not just any ordinary event. This is a small tribe that I feel I really can relate to over the longer term, and I can build a lot of strategic friendships moving forward.

Here are my random thoughts on the event.

A more coherent view on how Technology will disrupt the Legal sector is quite a few years away.

a) Lawyers and Programmers can work together but it may not be practical to do so

The most impressive segment in the event is by Kommerce headed by my old friend Karen Teoh who is COO of this initiative. In her company's segment, a full fledged lawyer was talking about his experience working with a programmer on building a Smart contract. My IP law professor David Llewellyn has taught me that this has been done before, but I have always found the idea impractical because the uncertainty of the Agile methodology and ridiculous lawyer billing fees would make the software ridiculously expensive.

So naturally I acted all snarky and asked about whether this was practical moving forward given that lawyers are so expensive. I also asked if the price of programmers and lawyers would converge over the long term. It was such a troll question, the audience was laughing at me after I was done.

b) LegalTech will fail in Singapore without Government intervention

Another harsh truth I realised about LegalTech is how fragile it is in a place like Singapore.

There is absolutely no way law firms will welcome disruption in their space because they really want to preserve their hourly billings. Even SAP consulting has moved into fixed project billing eons ago. Furthermore, lawyers are also protected by the Legal Professions Act. If you wish to provide legal advice you need to make sure you're qualified to do so. So LegalTech only has a very small area to play in if they do not wish to flout local laws.

The other issue is that Computer Scientists tend to be extremely hubristic and think that the world can change if we can build a distributed ledger around anything that they would like to disrupt or launch an ICO.

Two groups of highly intelligent, hubristic and arrogant professionals are going to have a really bad time relating to each other. It's like a couple destined for divorce unless the Government injects a lot of tax payers money to fund startups that have a 95% chance of failure. The government also needs to create a safe sandbox where IT guys can disrupt the legal industry with fewer consequences. Unlike FinTech, there is also less money to go around because of the localised nature of our laws. Law firms do not scale globally as well as banks.

Also, as I've spent time as an IDA officer and used to be one of those Barcamp groupies, I prefer to discount everything shared by accelerators since all ROI gains figures are unrealised as of now.

If local accelerators have a big exit story to tell, they'd be in your face by now, but all we're seeing is a lot of "pivoting".

c) There is negligible attention on the real problems faced by small law firms.

I am a lowly trainee in a boutique law firm, I have a lot of skin in this game. If access to justice is a problem in our society, then more junior lawyers need to be able to do independent research and give more strategic advice to clients. But instead, junior lawyers are too busy supervising paralegals who have to do the real heavy lifting in disputes. Photocopying, scanning, e-Lit submissions and typing.

There is too much paper involved in legal work and OCR scanning tools are not perfect. Documentation management involves windows folders and Word.

A trainee can spend an entire evening creating table of contents, making references and preparing documents for submission into the courts. As I'm on the frontline right now, I also witnessed how dangerous outsourcing this work can be and why smaller law firms prefer to avoid negligence liability so they do the work themselves.

In IT you can outsource because programming code can be corrected by a an IDE or a compiler. In legal work, the compiler is a human being with decades of experience.

d) Anyone getting into LegalTech need to ensure that they have other avenues to escape to when they fail

Some law student friends asked me whether they should heed the call of the accelerators.

Startups are sexy, startup exits and IPOs are sexier still. If you make it, you will be in the same category as the  Razer CEO. Always remember that there is one Razer CEO but many startup founders who failed. Many have spent their youths working on small, agile corporate firms that are informal and have a different social capital from the corporate MNC suit. This has negative implications on their net worth and prospects of finding a spouse.

If anyone wishes to go LegalTech, the most important priority is to work out a plan B. If you are a lawyer, ensure that you complete Part B and can run into a smaller law firm with your buddy's help after your startup tanks. If you are programmer, you have to keep picking new technologies or find a way to teach part-time in a Poly so that you can have multiple sources of income.

Oh yes, you also should read financial blogs so that you can develop passive income to make yourself more anti-fragile. The last thing you want to do is to have all your stock equity invested in one start up that may not be around 5 years later when you are closer to starting a family or having children.

Anyway, I think this is a new beginning for me. I will somehow get into LegalTech one way or another over the long term, but for now, I will observe and learn.

This sector has a long way to go before it can be taken seriously.


Friday, March 16, 2018

On Nicholas Taleb, leverage and ruin

Skin in the Game by Nicholas Taleb is not finance book per se but some of its ideas are interesting enough to challenge some of my ideas of leverage. I think Taleb's ideas are worth grappling with because they can potentially change your approach towards personal finance.

One particular idea is that ensemble probability is very different from time probability. If the model reflects the ruin of a few participants out of many, it is conceptually very different from the reality where there's only one participant who has to stop permanently the moment he is ruined by the markets.

One of the better things I did last year was to open a margin account. I wanted to continue to obtain high yields from REITS but I also wanted to buy higher quality REITs with a good story and stable management. The only way to resolve this paradox is to borrow $1 for each $1 I have and invest it in the better REITs on SGX.

When I talk about my approach towards leverage, I usually begin with a back-test. The models I ultimately employ for leverage always have a yield which exceeds on average 6.5%. After accounting for the borrowing fees, I tend to get 10% yields on my invested capital.

The more interesting feature of the models I employ is that I use semivariance which I combine with the expected return to figure out what happens in a 1 in a 40 year freak market. In a typical model involving REITs, I can backtest a modest 10% return with around 13% semivariance. So there is a 2.5% chance that I will drop 2 standard deviations down on a freak year or (10 - 2 x 13)=16% lose about 1/6 of my portfolio. ( But of course, market returns are non-normal so this will happen more frequently than what my models predict. )

As a 16% drop is only about half of the margin call of 30% ( Since I  limit my leverage to 200% ), I should not have to worry so much about hitting a margin call anytime soon as the probability is less than 2.5%.

Which brings us to the problem : So long as I maintain this leverage, there will be a chance that I will bust one day. Over time, this probability is 100%. Taleb says that "in a strategy that entails ruin, benefits never offsets risks of ruin."

This is where Taleb's insight comes in useful. If I am ruined, or gets a margin call, I can't play anymore. This is what Taleb calls the uncle point. Millenials will just say GG.

The moral of the story is this. If you leverage, you will definitely be ruined over time. In your universe, there is only you ! Your ruin may even drag down members of your family if you are not careful.

But I only leverage less than 20% of net worth and can comfortably live on the dividends of my un-leveraged portfolio. Furthermore, a margin call will only wipe out 60% of my original cash outlay into my margin account.

So the moral of the story is this : Leverage only your excess portfolio. Otherwise have a plan to eventually wean yourself out of a margin account.


Monday, March 12, 2018

The Art of the Good Life #14 : Circle of Competence

The last chapter was easy to read because Fuck You money agrees with me so much.

This week's chapter is the opposite because it really exposes just how dumb my latest career moves are.

The harsh truth is this  - Most of us have a really small circle of competence and this chapter reminds us that we should really just stick to it. If we know what we're good at, we should just focus on it and build a career around our personal strengths.

I think in the absence of passive income, this is something which I would have done. I would slowly retool myself into an IT Compliance professional and possibly try to stay that way for as long as possible. There are endless IT certifications to attain, in fact just before Law School, I got TOGAF certified so I am able to talk convincingly about Enterprise Architecture ( Most epic bullshit in the IT world which I'm glad did not catch on ).

But Fuck You money sometimes make you do really dumb things, often because you can and most folks, well, can't.

Legal work is so disjoint from my circle of competence as an engineer and a personal finance hobbyist, that I think I've been striving to promote my incompetence and being a sucker for punishment.

So, this chapter has a good point. I've been too focused on my deficiencies. But a lot depends on how you see what your circle of competence is.

If I see my circle of competence as IT, then I'm probably a real idiot for running to SMU to do my JD program. If I see my strength as learning new things and find synergies in different disciplines regardless of what kind of career I will eventually have, then I might have something to console myself with.

But still, thank god for Fuck You money. Nothing make idiocy viable as much as passive income.

A training contract is tough and pays less than what a domestic help gets, but I can survive this !

And I think there's a seminar on Legal Tech this weekend.

Maybe I'll find my niche there...


Saturday, March 10, 2018

Why Singaporeans tolerate inequality.


You see that parade of academics and rhetoricians rail about inequality in Singapore. Social commentators, however, are less willing to discuss the actual solutions to reduce the effects of inequality.

My personal belief is that Singaporeans on the whole are fine with inequality.

Yes, some Singaporeans will become scholars and yet some turn out to be merely statistics.

Nicholas Taleb's latest book Skin in the Game shed some light about the kind of inequality that we tolerate against the kind of inequality that should not be tolerated.  As it turns out the gap between the rich and the poor is a distraction that liberations employ to justify massive wealth transfers between the rich and the poor.

The is a more insidious kind of inequality at work. The concept Taleb employs is ergodicity.

Singaporeans can tolerate inequality so long as access to the upper classes is not blocked. Another words, the son of a taxi driver or a single parent family can rise up in society to become a Minister today.

This not only means allowing smart and capable guys like Chan Chun Sing to rise, it also must allow the so-called rich to fall.

Four years ago I retired because I was effectively financially independent. As a deliberate tactic, I ensured that my monthly dividend flows were about the same as the Singaporean household income statistic when my whole family got off the salary bandwagon. Four years later,  after law school, my dividend flows have gone up and so has my portfolio size ( thanks to some of my dabbling with leverage ).

At this juncture, I can imagine a liberal reading this and declare that a passive income investors will need to be redistributed to the poor.

But as it turns out, my dividend flow has been dropping relative to the household income for the past 4 years. There is a steady $1000 gap between what I collect and what most households earn every month now. This is one of the reasons I want to return to the workforce in spite of spending well within my investment income, Singapore society is the kind of society that does not let it's people rest. Even financial independence mean a gradual dropping of one's ranking relative to others.

So I have to pick up a McJob to remain average and respectable in this society !

So while our system introduces a substantial gap between the haves and have nots. Membership of the haves is open to everyone.

Which brings us to solutions which can make us uncomfortable and require the sacrifice of political capital.

The government cannot just create a system where the poor can rise to the ranks of the rich.

The rich must be able to fall.

Like many of you investors, wealth redistribution is something I would never support. I earned my wealth and my family has been becoming "poorer" over the past 4 years while I retooled myself to become a lawyer. Getting rid of assortative mating and mandating RGS girls take on ITE husbands is also impossible given that assortative mating contributes to 40% of inequality.

For a start, I can think of two subtle changes :

One possibility is that legacy admissions must be banned in Singapore. It does not make sense for the ACS boys who bullied me in the 1980s get a free pass to admit their kids to the ACS franchise and continue to benefit from being part of such an illustrious and well-connected alumni. This has to be earned and should not be a right based on a person's bloodline.

Another possibility is that Government Gebiz system limit some bids to companies of a specific range of sizes rather than favour larger companies. If some tenders are so big that a company needs to meet a paid up capital threshold to bid for the project, we have to accept that some projects can be so small that only a company that is small is allowed to bid for it. Readers in government can confirm with me as to whether this practice already takes place.

You see, you don't see Kuik Shiao Yin fighting to discuss these reforms in Singapore society.

It's always about the problem, never about solutions beyonds raping our reserves.


Thursday, March 08, 2018

Two abuses of words and labels

Let's go back to Budget Debate and how much Western educated liberals are working so hard to convince policy makers to start opening up our coffers spent the monies painstaking raised by the Singaporeans who came before us.

My first example is this stinker from the LKYSPP.  It is disgusting that this drivel is even associated with the name of our first Prime Minister.

The thought experiment is simple : Three children are fighting over a flute. Child A can play the flute. Child B made the flute. Child C cannot play or make flutes. The idea is that different people have a different ideas as to who should own the flute.

My personal belief is that the flute can either be given to Child A or Child B, but if given to Child A, then Child A is obligated to play sit o that all children can get to enjoy the music.

What I took offence about is that the analogy uses children implying that all policy decisions made by the powers to be impact only innocent parties.

Humanity is seldom innocent and blameless. I know because I now spend time in Family Court.

Find me a poor person struggling to overcome their personal circumstances and I will find you an irresponsible father who spends his days in Geylang and then complains that his children do not want to look after him.

I could have used a different thought exercise. You have three tumours but only the budget to remove one. Tumour A is benign. Tumour B is benign but awful to look at. Tumour C is cancerous and awful to look at. Which tumour do you eliminate ?

This evokes a different set of emotions entirely.

My second example is Kuik Shiao Yin who probably thinks that real life is as easily solvable as simply writing a GP essay. Some articles on her latest speech can be found here.

My beef is that allocating 50% NIRC is an arbitrary figure. Who died and gave Kuik the right to say that decreasing spending on the present is pragmatism whereas the opposite is being idealistic ?

I think no one has right to arbitrarily label a mathematical exercise. I think decreasing the NIRC cap to 40% is prudent and increasing it to be irresponsible. Does that make my label better than Kuik Shiao Yin?

Anyway, win or lose, we can always duke it out at the ballot box during the next elections.

Oh, except that Singaporeans never did elect Kuik Shiao Yin.

And Happy International Woman's Day !

So liberals, can we stop encouraging the rape of our reserves for a change ?

See the use of words matter !


Monday, March 05, 2018

The Art of the Good Life #13 : Fuck You Money


Because this is a financial blog, I would say that this chapter is the only disappointing one so far.

The author positions fuck-you money as having one year of living expenses so that you can say "Fuck You" to your asshole boss and then storm out of the office never to come back to a dysfunctional workplace. 

What a horribly bad idea. In this age of tech disruption, some knowledge workers may be unemployed much longer than a year and this idea might only work in a welfare state. Alternatively, you can get an Uber license.

A better solution is to accumulate enough fuck you money so that your dividend income is equivalent to the salary where future salary increases lead to diminishing returns in personal happiness. This translates to about $75,000 in annual income. As it turns out, investing a million dollars at a return of 7.5% will be able to do exactly that which is why it is unwise to scoff at people who aim to become millionaires in society today.

A million dollars is not very meaningful, but $75,000 in annual income without lifting a finger is quite a remarkable

For most ordinary people who are not investing superstar, thanks to Budget 2018, the Lion-Philip SREIT ETF no longer pay 17% taxes, so you can invest your money tax-free and receive dividends of more than 5% with a reasonable prospect for capital gains. To generate $75,000 a year, you will need a portfolio size of $1,500,000. This is challenging for a single person but for a working professional couple.

The rest of the chapter has some down to earth advice for people :

a) Don't react to minor fluctuations to income or assets. I think it's easier to avoid thinking about market volatility if you have a day job and a large asset pool.
b) Don't compare yourself to the wealthy. Also hard because you are trying to become wealthy. I think its better not to compare yourself with the poseurs because the truly wealthy are quite frugal and have very little to show.
c) Live modestly. Which I thoroughly agree.


Saturday, March 03, 2018

The Influence of Religion on Personal Finance


Today's topic is going to be a teensy bit controversial, so I put up a picture of controversial person. Some other financial bloggers have commented that I am a Kong Hee like person when I give my talks, I am quite flattered by that remark. In fact, I followed Kong Hee even as an atheist when he talks about modern topics like postmodernism. There is something mesmerising about his speaking quality, something I was unable to experience even after spending 10 years with the Toastmasters movement.

The working paper is entitled Randomizing Religion : The Impact of Protestant Evangelism on Economic Outcomes by Bryan, Choi and Karlan. This paper is making huge waves in social science circles and have been mentioned by Tyler Cowen and the Economist.

Internal Care Ministries (ICM) collaborated with a team of economists to spread religious teachings to 6000+ Filipino families, then based on what was taught, the economists tracked their economic outcomes. This study would confirm the impact of religious values on economic outcomes.

To a personal finance geek like me, this is seriously awesome shit !

The religious values curriculum is covered by a pastor. There is also a livelihood segment on what good works should be where some common sense advice of money is taught. The researchers are highly meticulous and a large part of their work was done to disentangle the effects of religious values against livelihood advise.

The results are a goldmine that can lead to future study :

Having stronger religious values do, indeed, lead to higher incomes largely because it makes religious followers grittier. However, this effect does not translate to greater wealth, the researchers argued that there was no time to measure this effect.

However, religious values training made participants more aware about their relatively economic statuses and made believers a lot more discontent with their lot in life. Religious training reduces a participant's perception of well-being. ( These are poor Filipino villagers, after all. )

I am going to just stop here because I don't want to kick a hornet's nest and draw any conclusion that is not written in the working paper.

I leave it you readers to think about how your personal values has affected your relationship with money this weekend.

The effects of your religion and values cannot be discounted when you think about how they have shared your economic destiny.


Thursday, March 01, 2018

The Influence of Language on Personal Finance


This is the single most momentous event in Fantasy Literature with Legend of the Condor Heroes being successfully translated into English. Translation of this work is so difficult and thought to be previously impossible, even the Economist published a book review last week. I was never able to watch a complete series on this storyline so I was kept mostly in the dark when it comes to Jin Yong's work, having only completed the Duke of Mount Deer series which starred a young Tony Leung Chiu Wai in the 1990s.

Reading this in book form is epic. Imagine the possibilities - we could read the same book as part of English Literature class but also as part of Higher Chinese. This will resolve the issue of CL2 being boring. Dream of the Red Chamber is about an effeminate man-child and his side chick, nothing can make you lose interest faster than being forced to read this kind of drivel. Legend of the Condor Heroes features non-stop Kung Fu fighting that pits the Seven Freaks of the South against the Twice Foul Dark Wind. Even Tolkien is boring compared to Jin Yong.

I see my daughter's love for Mandarin being killed slowly by the current education system where every mis-stroke is being cruelly penalised in Primary 1. This is slowly driving my daughter to become a banana person like me.

Ok, let's talk about language and personal finance.

The impact of language on personal finance is profound and social science is only coming to grips to this new reality. In a working paper entitled The Effects of Language on Economic Behaviour : Evidence from Savings Rates, Health Behaviours and Retirement Assets by Keith Chen of Yale University, thinking in particular language can shape your savings behaviour.

Some languages, like English and French, have a specific grammatical framework to mark out a future event. eg. I will be going to a seminar. Clearly the seminar will happen in the future.  Other languages like Mandarin, do not have a future tense, Wo3 Qu4 Ting1 Jiang3 Zuo4 does not clarify whether the speaker is going to seminar right now or in the future. You preface it with Ming2 Tian1 if you want to specify the time as tomorrow.

Social scientists discover that people who think in a language like English and French have a tendency to distinguish their future selves from their present selves. As a consequence of that, the savings rate and accumulated assets of these people are low. In contrast, folk who think in Mandarin, German or Malay have higher savings rates and larger accumulated asset base because the delineation of the future self with the present self is less clear. Even within a country like Switzerland, German speakers were found to have higher savings rates than French speakers.

The current explanation is that we will take action that will benefit our future selves if the future does not seem to distinct from the present.

Some findings within the paper is really surprising.

There are larger proportion of English speakers in Singapore compared to Malaysia. And as a consequence of that the paper reports that the savings rate of Malaysians exceed Singaporeans !

I'm sure the folks who are most excited about this finding might be the old school Nantah Graduates because it vindicates the bilingual policy. 

But can making your children act and function in Mandarin or Malay make them more conscientious and money savvy?

This is, indeed, a possibility.

Hopefully, this weekend, we can explore the influence of religion on our personal finances.


Tuesday, February 27, 2018

The Art of the Good Life #12 : The Things that you buy leave no trace

When an experiment is conducted where researchers ask participants about how much a recently bought object brings them happiness, it was found that an expensive high-end car brings more personal satisfaction than an average vehicle. However, when the same participants were asked about how they experienced their last trip, the price of the vehicle did not affect their experience.

This chapter is really about two concepts that are commonly in the local financial blogosphere.

The first concept is that when it comes to purchases, experiences always trump things. I have tried to explore various counterfactuals but I can not come up with anything that contradicts this. My only conclusion is that some experiences lose their value when they lose their novelty. Your fourth Hokkaido trip may  be much more boring than your first. Of course, you can simply buy more and more exotic experiences. 

The second concept is that of the hedonic treadmill. After living in a landed property, there is a tendency to get jaded so it no longer brings you pleasure. In fact, losing your landed property can bring you lots of misery.

I am currently grappling the consequences of accepting these ideas as fundamental truths. They seem so powerful and almost spiritual in it's universality.

Suppose if we can retreat into a life of computer gaming and binge watching of Netflix where Internet media repeatedly comes up with novel ways of entertaining us, isn't that a life of complete and utter satisfaction ? Then why do people even bother setting up families and having children when they can defeat enemies in Warcraft, run mega corporations in Eve or explore different universes by binge watching series ?

Social science is catching on to this new reality.

The useless class in the US are lowly-educated jobless males who no longer participate in the labour markets. They started showing up in labor statistics since the Great Recession and labour participation rates never recovered. Shocklingly, social scientists are detecting high levels of life satisfaction amongst these guys. I've always attributed this to better computer games, especially RPGs, which can credible make up for the lack of achievement in anyone's lives. I would forget that moment as a 9 year old that in Dungeons and Dragon, you can have a Strength of 18 and can level and get better as you murder more monsters.

We can laugh at hikkikomori of Japan and label them as losers but the latest Economist article last week is gushing about how satisfied and happy these guys are living with their parents and having no responsibilities of their own.

I think Asia is undergoing some sort of Renaissance that sees the otaku and hikkikomori transform into a phenomenon that is  more acceptable in society. The Japanese have this new term to describe these men : The Satori Sendai or the Enlightened Generation. China has also followed suit with gentler labels like Buddhist Youth.

Right now, I don't have a grand unified theory that synthesises all these concepts but a combination of technological disruption, augmented reality and virtual worlds is normalizing the destruction of ambition on our men. I leave you to decide whether this is a good thing.

It gets more ludicrous once you include the financial perspective.  A single man may only need $150k-$200k to generate $1,000 a month to live a hikkikomori life of living with parents and playing CRPGs all day. Parents can even be given a small allowance.

So perhaps it's that little bit of financial savvy can turn a hikkikomori to a satori sendai. 

This way, Capitalism is the new Buddhism of the masses.


Sunday, February 25, 2018

Some quantitative characteristics of Cryptocurrency

The source of this article is the Cryptassets book by Burniske and Tatar. I also draw a lot of quantitative isights from Cryptocurrency : A New Investment Opportunity by David Lee, Li Guo and Yu Wang that is published on Vol 20 Number 3 of the Journal of Alternative Investments, this article from David Lee is possibly the most objective source of information for serious crypto investors that I can think of so far.

Here are some of insights :

a) A cryptocurrency index exists in the form of the CRIX index.

The bulk of academic research is done on the CRIX index that SMU played a major role in its creation. The index is generally based on the market capitalisation and liquidity of the underlying coin and is also fairly dynamic with weights being revised on a quarterly basis.

Sadly, it would be a while before an ETF based on the CRIX index is launched in the markets. But I can imagine if that every happens, demand for such a product would be huge. For now, you may have to settle with buying the top 20 coins in market capitalization to approximate the performance of the CRIX index.

b) Superb market performance of crypto-assets is not really meaningful moving forward.

The performance of crypto-assets accounting for 2017 is ridiculously good.  The paper reports  possible annualised return with a Sharpe ratio of 11.64. Warren Buffet over his career can test around 0.76 and my own backtest REIT portfolios fare much worse.

Too much of current performance of crypto is based on mania and investor sentiment. This performance is not likely to be sustainable moving forward. In fact, my guess is  that 2018 is expected to be a bad year as a historical bull run on bitcoins has been followed by a year of tragedy for crypto investors.

c) If you hold too much crypto-currency, you will never get a good night's sleep.

Cryptocurrencies exhibit negative skewness and a high kurtosis. This means that a negative swing against an investor is drastic and happens with a much greater frequency than the normal distribution.

Bitcoin itself has a kurtosis of 8 which means that it has fat tails. The more obscure coins can have a kurtosis over 20. The normal distribution has a kurtosis value of 3.

d) Cryptoassets are uncorrelated with the markets.

Generally speaking the correlation of cryptoassets against traditional instruments is low so they are fairly effective as a portfolio diversifier. Correlation of CRIX with S&P500 is 0036, treasury notes is -0.02. Highest correlation is with Gold at 0.036.

Do note that these correlation numbers break down when the markets turn south.

e) Conclusion : Limit Cryptoassets to 1% of your total net worth. It can replace your Gold holdings.

I have chosen to follow the Cryptoassets book rather than the David Lee article and err on the conservative side to suggest an asset allocation for cryptoassets. For folks who are willing to take more risk, it may be useful to read the academic paper that has a different prescription.

Investments into cryptoassets make a lot of sense if you limit it to 1% of your entire portfolio, this 1%  should also replace your Gold holdings.

Right now, I have way less than 1% of my assets devoted to crypto-assets. This may change when I start getting a full salary in the middle of year.


Saturday, February 24, 2018

Six compelling reasons for cryptocurrency.

I've been delaying this article during the ramp up of cryptocurrencies but since the prices have sort of corrected and calmed down, it is time to look at cryptocurrencies without all that excitement from the bull market..

Fortunately, David Lee Kuo Chuen, the lecturer who taught me fund management more than a decade ago, is the invited editor for the latest Journal of Alternative Investments and articles in Volume 20 Number 3 seems to be a very objective look at this new asset class.

The next few articles on this blog will be cryptocurrency related but, hopefully, hype free.

Today we will focus on six compelling reasons why cryptocurrencies should not casually dismissed as yet another bubble like Tulipmania. Cryptocurrencies is a significant advance for humanity, much like that moment we invented the idea of limited liability in companies.

Here are the six reasons for cryptocurrency :

a) Non-correlation with traditional asset classes

The first reason is that crypto-currencies are not correlated with the equity markets in general. While this is generally true, remember that during the massive market correction, cryptocurrencies had a mini-crash of it's own. One common theme that keeps repeating itself is that in a major market crash, every asset becomes closely correlated to each other.

b) Transparency

Blockchains have a unique ability to centralise trust. This provides transparency for philanthropy and other funds. This is a very understated advantage.

c) ICOs address the problems faced by  startups

As much as I refuse to touch ICOs ( It seems that all you need is a convincing White paper ), blockchain technology finally takes the power away from a VC and puts it in the hands of an entrepreneur. This is a new form of capitalism that can make or break our personal finances. Those who can tell the good ICOs from the scams will be able to enrich themselves very quickly.

d) Decentralised exchanges resolve the issue of illiquidity

The problem of illiquidity of early startup investing instantly disappears because decentralised exchanges gives you a constant exit after you put money in an ICO. Case in point, getting an exotic alt-coin like Doge Coin is way easier than buying one lot of Global Testing on SGX.

e) Cryptocurrency as a new asset class

I think David Lee's hypothesis is that Cryptocurrency is a completely new asset class. It makes a lot of sense because one possible definition of a  commodity is a valuable input to an industrial or agricultural process. Cryptocurrencies are not inputs to any process. More interestingly lawyers are;nt even clear whether when you deposit some crypto into an exchange, you are considered a debtor or someone with full property rights. So cryptocurrency is truly a unique asset class on its own.

f) Fractional ownership

Because you can have such a small component of a bitcoin, imagine the power of fractional ownership of assets and what difference this can make to really poor economies.

More hardcore details to come over the weekend.


Wednesday, February 21, 2018

Budget 2018 discussions mirrors our journey towards Financial Independence


On the whole, we've had a fantastic 2017, which was why Budget 2018 was not a punitive one even though it was a mid-term budget.

The aftermath of the Budget is interesting because discussions about NIR returns mirror the internal discussions we have on our journey to financial independence.

Ray Dalio in his book Principles has a very elegant way of describing what happens when someone becomes financially independent.

There are two approaches to living life post financial independence :

a) A certain portion of FI folks would want to Savor Life.
b) And yet a substantial number of financially independent folks want to make a Bigger Impact in this World. 

Personally, I started out really wanting to savor life after my failed stint in the public sector, but after tasting Law School and seeing how a little bit of knowledge can have such a profound impact in the world, I am beginning to see the wisdom of trying for a bigger impact on this world.

Because there are two ways of seeing the ultimate outcome of one's financial independence, it is not surprising to see Singaporeans divided on the issue of the 50% cap to the NIR.

One school of thought represented by academics like Donald Low is that if we can increase the cap to 60%, we would never need for a 2% GST increase in 2021. This is definitely an attractive option for many citizens. Why not spend more for ourselves and retain less for future generations ? I am confident that Donald Low's numbers are well-researched. There's no reason to doubt him here.

But my school of thought is the direct opposite of Donald Low. Why not lower the cap to 40% and raise the GST to 10% immediately? I always felt that I would like my children to have a more comfortable life although I would like them to choose to make a bigger impact on the world than merely savoring it more. My proposal will allow the government bigger surpluses in the future so that compound interest would allow us to do much more in the future. This change may even mean more assistance programmes for the disadvantaged.

So 50% is an arbitrary number chosen by the government with the support of the electorate.

Both me and Donald Low would have to accept that there are going to be different kinds of Singaporeans. Some believe that they deserve instant gratification and demand to use up more of the reserves immediately. Others like myself think that some struggle is necessary for the nation make an impact to the world at large and would always try to emulate our ancestors by taking less than future generations.

I try to justify myself by saying that my personal life is congruent with my political inclinations and views on taxation. I started saving 50% of my earned income rather early in life and spent close to a decade saving 100% of my take home pay living a simple life on my dividends. My first act upon retiring was to go back to retrain myself.

( There are certainly financially independent folks who have inherited money and put 100% into savoring life. That, to me, is the reason why we no longer have the Roman Empire. )

Of course, if you agree with me, you would also have to be aware that there are consequences to adopting our set of conservative beliefs.

One consequence is that I am willing to accept more inequality in society than Donald Low.


Monday, February 19, 2018

The Art of the Good Life #11 : The Focusing Illusion

Suppose you had a really bad day in the office. Meetings were extremely long and dwelled on unimportant matters. Your boss is also giving grief once again over small matters like the formatting of your powerpoint presentation.

After a tough day at work, you managed to crawl out of the office to attend a financial talk and the guru then paints you a wonderful picture about financial independence.

The guru, a master of failure pornography, first tells you a story of his life, how he never did well in school, how he was a dropout from the education system, and constantly underestimated throughout his entire working life. He then talks about how successful he is today, shows you nice pictures of money being credited in his bank account whether through means via MLM, internet marketing,property speculation or forex trading. He then goes for the kill... He talks about how his financial independence allowed him to give the middle finger to his boss and finally leave the rat-race.

You are inspired by the inspiring talk. The guru is a school drop-out. You are  professional with a decent degree. You start to ask yourself,  how can he be the guru and you the low-wage corporate slave? The guru then offers you a solution. With a low fee of several thousands of dollars, you can get 1-1 mentorship and can get out of the rat race.

Mai Tu Liao ! You rush in to make payment...

I liked to see myself as a finance speaker who takes the high road.

The last thing I want to do is to hijack your amygdala and paint you a wonderful picture of what to look forward to in your journey towards financial independence. Perhaps I am irrational, my gang at BIGScribe wants to serve a calm and rational crowd which is why we put such a huge premium in research and are highly evidence-driven when we make an assertion about what investments work. While we may not be as persuasive as that finance guru I spoke about,  I think deep inside we want to be seen as being intellectually superior and have a system that can be  replicated by a smart, well-informed, and educated audience.

Naturally, our business makes less money... for now.

What makes these gurus so powerful is the rampant abuse of the focusing illusion.

If I bring your focus on how inane your last meeting is, or what a nit-picker your boss is in your last encounter, I can probably make you discount the value of having a good corporate career. It is not difficult to trick you into focusing on what's the shittiest thing about your working life. For government servants, I can possibly hurt you quite badly if I talk about procurement and GeBiz. For MNC workers, I just need to talk about late night conference calls and how NA and EMEA regions just can't fucking agree and advance the meeting agenda so Asia can get some sleep.

But work is more than just conference calls and procurement paperwork. Sometimes, you get a connection with a co-worker gain access to workplace gossip. Some other time, your company takes you out for some Lou Hei ( which I have missed for the past 4 years )! You also meet like-minded people from the same economic strata at work so it's a great source of friends.

When you look at the bad and the good in totality, having a career is not as bad as when you are just focused on the negative parts of the work commute and administration.

After leaving the workplace four years ago, I definitely achieved a high degree of personal satisfaction, I no longer have senseless paperwork to do and feel unmotivated when a bureaucrat forces me back to the drawing block over a small technicality in my paperwork.

But in essence, I'm just replacing some bad experiences with other bad experiences when I left the workforce for Law school.

Some administrative work in law school can be just as bad as procurement work in the public sector. I have spent time trying to trim down the text of fellow classmates to get our research paper within word count. We still do this for Court of Appeal paperwork that is limited in number of pages. One particular fight I had with a fellow student over which discount rate to employ to price intellectual property was more violent than any work conflict I ever had in my entire life ! Don't even get me started on arguments over the Law.

I guess the most important lesson in this chapter of the book is to review your life in totality and not to let some guru hijack you emotionally so you end up helping him attain his financial independence.


Friday, February 16, 2018

Personal Update - Happy Chinese New Year of the Dogg !


I had an inkling that the Year of the Earth Dog is going to be a fairly good year for me. Based on the stem and branch Chinese horoscope system. Earth has always been an element that I am deficient in. And a Feng Shui master hired by my boss confirms that I will have a great 2018.

Of course, 2018 is a culmination of years of hard work as I try to enter into a completely new industry. Here's a quick update :

a) Legal Training Contract

I have spent 2 months on my training contract working on a few financially complex divorce cases and some smaller corporate law disputes. I'm still grappling with the lifestyle of a litigator and cannot really judge whether I am suited for this lifestyle. My largest struggle is with the amount of attention to detail required to do the job and the little autonomy I have if I decide to pursue this as a lifelong career. The intellectual challenge and strategic planning component of my work is fun but remains too small a component of my day.  Most of my life is dotting every "i" and crossing every "t" - something a guy is not really proficient at doing.

One of concerns is that it may take a decade so as not to suck as a litigator, and as a mid-career hire I might not have that luxury of time. Kudos to the 20-something year olds who qualify to do this kind of work, it's a craft that they have decades to hone, and something people will pay top dollar to.

b) Financial markets are shaping up ok and I got a "performance" bonus for my work.

As it has been a fantastic year for the financial markets, I was able to expand my father's portfolio by quite a decent amount by strategically shifting into Tech over the past 2 years. Now I'm shifting gears and moving the portfolio into counters that benefit from higher interest rates. As the portfolio is sufficiently large, there is no longer any sense of urgency to put the money into higher yielding counters anymore so I can be more thematic with my investment approach.

I also felt quite good to get a "performance bonus" for my work on the family portfolio which would be farmed into my personal margin account. With any luck, I would be able to shift back into growing my main portfolio once I re-establish an earned income which I have missed for the past 4 years.

Perhaps we're due for a major recession, and it's best be employed to farm 100% of my salary into the markets when that happens !

c) Fresh new initiatives with BIGSCribe.

I am really excited to talk about our latest initiative with BIGScribe.

In the past, BIGScribe has always been paid seminars with bloggers talking about whichever topic is hot on the minds of the readers and fans. This year, we managed to get an opportunity with an major education institution to establish our first flagship product - a regular workshop that focuses on Financial Independence. This can potentially plug our biggest weakness as a company - we need a regular source of business that people will be willing to pay us for.

Right now, we're not even done with fleshing the outline of our work but I am already picking up a lot of new stuff that I was previously unaware of. As far as I am concerned, designing the curriculum and exercises would have honed my money making skills with company revenues as an added bonus.

I expect this program to be the most erudite and well-researched product in personal finance in Singapore. We remain unbiased and focused on helping our clients achieve financial independence at a much younger age than our statutory retirement age. And this will be conducted by folks who have actually attained financial independence themselves.

The Year of the Dog is where good things must happen for me. it is time to harvest from all the hard back-breaking work I've been putting on the table.

Wang wang !


Wednesday, February 14, 2018

Happy Valentine's Day !

I try to come up with something every Valentine's Day but this year I have said everything I wanted to say so I was about to skip it until I read something really interesting about marriage and divorce in Daniel Pink's When.

So here's something for you to think about this Valentine's Day.

a) It's not a good idea to get married if you are too young or two old.

If you marry at 25 years old, you are 11% less likely to divorce than if you were to get married at 24. Divorce rates drop as people marry at an older age until age 32. After which the rate of divorce actually goes up by 5% every year.

Once you are single for too long, it's hard to let go of that kind of freedom.

b) The more education you have, the better your marriage.

Marriage satisfaction is a lot higher if you complete your education prior to getting married. At comparable age, ethnic group and income, a couple that completes school tends to stay together.

c) Do your due diligence during the dating phase.

Couples who dated for at least a year have a 20% lower rate of divorce. Couples that dated for longer than three years are even less likely to split up. This makes dating a serious investment of a guy or a girl's time. Sort of makes all those discussion about why it's so goddamn rude to pay for a date kind of trivial once you see the big picture. Guys have a few years to demonstrate their capability as husband material.

Of course, no discussion of marriage would be entertaining without some interesting analytical data on divorce. Apparently divorce rates peak on March and August. The hypothesis is that some couples try to endure a failing marriage throughout the holiday season and March is around the time people lose patience with each other. August is likely because it is the end of the school year in America.

How does it all fit into your plans for financial independence ?

Well, an alpha male graduate at age 25 who aspires towards financial independence has about 4 years of uninterrupted work where he can work overtime and slave for his first $100,000. Thereafter, he can start dating at around age 29 for three years before getting married at 32.

This is a fairly compressed schedule and you may want to consider some of my more controversial ideas of leveraging a low beta high yield portfolio to speed things up a little.

Still, I don't think there's a need to go Dutch on a first date. Just go to a hawker centre and then be gentlemanly enough to offer to foot the bill.

Your financial independence will not skip a beat.


Tuesday, February 13, 2018

The Art of the Good Life #10 : The Five Second No.

Human beings have evolved to cooperate with each other which is why our dominant rule of thumb is the rule of tit for tat.

We are wired to cooperate and help a fellow human being unless that other human being refuses to cooperate with us. In such a case, we retaliate. Tit for tat is a relatively good strategy and can be said to be optimal in some strategy games.

But there is dark side to employing this strategy. We have developed a habit of saying "yes" to a request without really assessing the opportunity cost of agreeing to do something for someone else so much so that some people can spend their entire lives just trying to please other people.

So Charlie Munger of the Berkshire Hathaway fame suggests giving the "five-second no". He would think about a random request for five seconds and then just say no. Some people might be disappointed at rejection but Charlie found that it seldom hurt him over the longer term. Instead, people knew where he stood when it comes to the use of his time.

The book does not consider the middle ground which was amply explored by Mark Manson in The Subtle Art of Not Giving a Fuck.

As a trainee in a law firm, the value of my time is negligible. As I don't have a lot of social capital in this new alien industry, I can't really say no to a lot of things. In fact, I have to say yes and then do my best to meet whatever requests that come my way. If a trainee eventually rises to the position of a partner, his time may be worth thousands of dollars per hour. His opportunity cost is so high that he would have to say no to many things unless the other person agrees to be billed for his time. ( In fact, he might even have to say not to his own family )

Whether we can say yes or no largely depends on how much we need the cooperation and support of the folks around us.

If we exist in an environment where there is a lot of interdependence, then we should always say yes in the hopes that others will help us when we find ourselves in need. In an environment where we experience a lot of independence ( much like financial independence ), it is much easier to just pause for 5 seconds and then say...

...fuck no.


Sunday, February 11, 2018

Ready for Budget 2018 ?

The good thing about not being chosen to be one of the beautiful people to promote Budget 2018 is that I am free to write whatever I feel like writing on Budget 2018.

Saltiness aside, here are two things to look forward to in 2018.

a) GST increase

My personal guess is that the GST increase will be gradual but extensive. So perhaps we may see a 1% increase every 1-2 years until it reaches 10%. This will immediately have a negative impact on the purchasing power of the bottom half of income earners in Singapore.

What I am doing is that I have started rushing to subscribe to the magazines I read. I bought a 2 year subscription to the Economist last week and might take some steps to cut down on my telco expenses.

b) More Immigration

We don't really know when the floodgates will be open again but I expect the consultation with the citizens to be just lip service. We are aging rapidly and the government WILL DEFINITELY sacrifice political capital to bring in more foreigners.

Once foreign technologists and engineers start gushing in to take up roles in our Silicon Valley, expect salaries of folks in IT and Tech to be held back once again for a decade or so. The biggest losers are Polytechnic and ITE graduates who are failing to clinch permanent jobs even when foreign workers are being curbed. Worse, during the flood of foreign workers prior to the 2011 elections, Polytechnic graduates are hardly getting any increments while University graduates just zoomed ahead. This can only make our education system more competitive and stressful. 

Still, there is reason to be less apprehensive of immigrants this time round. Our infrastructure is more or less ready for more people on this island. Landlords and investors have reason to rejoice as there will be more demand for leases as the foreigners reinvigorate the economy. Many Singaporeans with two homes can look forward to selling both to an immigrant family and settling down in Australia instead.

I expect the legal sector to benefit from immigration as well. Our numbers remained heavily under control and a higher population will always lead to more disputes and greater demand for legal advice.

c) Wealth Taxation

As we have started talking about immigration, I think wealth taxation will not be high up on the government's agenda. We're still trying to build our REIT market and startup ecosystem. This means rolling out the red carpet to International wealth.

So long as immigration can return to Singapore, the government can finally end those silly PIC credits for SMEs which opens up opportunities for cheating. This can free up more money for the aging population.

Whatever it is, I expect 2018 to be a better year for the Rentier-Supermanager. More rents, more income for those with professional skills and financial assets that command a higher value.


Saturday, February 10, 2018

AAR : Profiting from Macroeconomic Trend Shifts

We held a seminar on Macroeconomic Trend Shifts last Thursday night. I will leave it to the other bloggers Xeo Lye and Elvin Liang to talk about their respective sections. As for me, I will just provide a short review of my segment.

My official role for the day is MC. This is an unpaid role I volunteered for because I felt that I can develop a new kind of competency and contribute to BIGScribe. I also wanted to attend the other talks for free.  Also, the directors have, in the past, commented that I'm a very "Kong Hee" like on stage, so I really want to hone this ability before I have to present a client's case in Court.

Normally an MC would just introduce the other speakers, wish the audience farewell, and consider his job done. I injected a slight twist to my job role.

To introduce Xeo's speech, I first gave an overview on Macro investing and told the audience that it involved different asset classes. Then I focused the audience on the dramatic events of the past week and tried to explain why there was market downturn. This gave the audience something to think about before Xeo Lye's segment.

Because I had access to Elvin's slide, I knew that the audience may be inundated  by  the sheer amount of information on how to interpret various economic events. So I built a "cheat sheet" on the various ETFs on the SGX that investors can buy prior to Elvin's talk.

How I could have done better ?

I think I should have added two slides before the Q&A section and gave just one example on how to invest based on a leading indicator that Elvin mentioned in his talk.

On hindsight, I should spoken about the rise in the PMI and how a portfolio of dividend stocks in manufacturing can be employed to not just produce passive income, but ride on the growth trend at the same time.

Nevertheless, due to the lack of time, I might not have been able to pull that stunt without eating into Q&A further.

Well, I hope to get more MC gigs in the future !

Monday, February 05, 2018

The Art of the Good Life #9 : The Authenticity Trap


Suppose you and a Japanese food connoisseur friend go to new restaurant and order a bowl of Ramen. When the Ramen arrives, your friend is aghast !

There are fishballs in his ramen !

He says that the ramen is not authentic because fishballs are not part of Japanese cuisine. In fact, your friend declares that bowl of ramen as Chinese food and unworthy of his meticulously curated Japanese food tasting tastebuds. A few days later, you check out the Wikipedia entry on Japanese Ramen and you find out that Japanese noodles originate from China.

So is the fishball-laden ramen authentic ? Or are all Japanese Ramen dishes a shallow imitation of Chinese noodles ?

Take another example, in your Tinder profile, you declare that you would like your significant other to be an authentic guy. Closer to Valentine's Day, you manage to get a hot date with your profile. The guy, during the date, tells you that the reason he wants to meet you is because he thinks your profile picture is worth masturbating to.

You get angry and confront that creep !

But he says that he's just being authentic by revealing his real thoughts regarding why he wants a date with you. He thought you would find his authenticity refreshing because that's what you want in a guy !

In both cases, Authenticity is a trap and definitely an overrated thing to aspire to.

Instead the book suggests channeling President Eisenhower and developing a second persona as an alternative to becoming more authentic.

When you wear the mask of a second persona, you make a point to keep all promises that you make. You also develop a set of principles that you apply consistently everyday in all your professional engagements so that the folks you encounter always know where you stand on certain issues.

This idea of a second persona is a great idea.

To navigate the complexities of modern life, we take on many roles. There should be a persona for every role that we play.

It sure beats trying to be yourself and getting rejected over and over again because of that.


Saturday, February 03, 2018

Brutal truths about non-elite JC education.

First of all, my heart goes out to the students and alumni of the JCs which got merged. Years of history were flushed down the drain when the authorities decided to make it happen. What made me particularly furious is that non-elite JC students were made to memorise answers from top JC students because educators do not have the confidence that they can come up with arguments and ideas of their own. This was unheard of during my time.

The unPC reason for this merger is that the JCs were not elite enough. As much as we hate to hear this, this is a good answer.

JCs were merged because they were not elite enough. End of Story.

Here are some of my other thoughts on this matter :

a) Instead of blaming Eunoia JC, you should blame the Polytechnics instead

Certain quarters of the Web had their ire targeted at Eunoia JC and asked why Eunoia was not terminated instead. Let's get real - Eunoia is an elite JC with a specific targeted audience of IP students. It is an elite JC, why should it be shut down ?

I believe that the merger of JCs largely occurred because the recent policy is to include Polytechnic students in local universities in numbers that is lot more generous than in the past. This creates the illusion of inclusivity in our society. As such, the elite O level cohort, that in the past has almost exclusively gone into JCs,  has redistributed themselves in a 1:4 ratio across Polytechnics:JCs, this dampens the quality of intake of a non-elite JC if the total JC intake maintains its current size.

b) You need to understand the concept of the Golden Road in Singapore education

I came up with the metaphor of the Golden Road to see if things can be explained in a better way. The Golden Road is part of the education system that puts a person into a local university from primary school.

The Golden Road during my time was simply Primary School, Secondary School, JC and then University. These days the road has many splits and forks and for some really elite folks, it can now look like : Primary School, IP Program, University. The government clearly wants to build another Golden Road based on Primary School, Secondary School, Polytechnic and University.

Staying on the Golden road is crucial because it virtually guarantees a middle class existence. For most folks who succeed, it means $3,600 starting pay and a much easier time finding a spouse.

But the Golden Road has limitations. The width of the road must be kept small so that the middle class will continue to be prosperous. The government currently wants to widen the Golden Road to cover 40% of the primary school intake but widening it too much will result in an overeducated but underemployed population much like that of Japan and Europe.

So there are physical limits to the Golden Road. Personally, I doubt the Golden road can accommodate 40% of the population, I speculate that the final policy effect is that SUTD, SUSS and SIT will become second tier degree programs that will have incomes about 10% below the other universities. Let's see whether I am right in this regard.

c) The Golden Road is a Road of immense angst and unhappiness

Given the pressure to stay on the Golden Road, the pressure will be immense. On the Golden Road, emphasis will never be on education and learning.

The emphasis is on scoring and passing exams of increasing difficulty. Learning occurs as an incidental effect because of the emphasis on scoring well for exams. Teachers will be benchmarked primarily on scoring of their students. The Golden Road emphases on signalling and weighing students against one another, so don't expect to learn skills that are immediately practical in the real world.

And there will be cases of depression and suicide.

Ultimately, the brutal truth for non-elite JC students is this :

The Golden Road is brutal and inhumane. You can step off the Golden Road and attend a Polytechnic where even the top students there actually want a harder curriculum, but you obviously chose this road because you want a guaranteed middle class existence.

d) The Golden Road is a public-private sector collaboration

Why do I have so much conviction on this idea of the Golden Road ?

Professional Service Firms are starting to realise that the best path to profitably comes not from skills but from insecurity of their human capital, this pushes people to work 100 hour weeks. Year after year, thousands of students graduate into law, accounting and management consulting firms which have mastered the ability to turn this form of personal insecurity into company profits. Professionals and kept on their toes because the hours billed are benchmarked against each other.

You can work yourself literally to death, divorce or insanity under this system !

Our education system has decided to collude with this industrial complex to make Insecurity Singapore's greatest human capital export. Insecurity makes Singapore a great nation that is the envy of the International community.

I think there is a way to beat this system : Read our financial blogs and we will show you how you can be free from all this bullshit.


Thursday, February 01, 2018

[ Next BIGSCRIBE Event] Profiting from Macroeconomic Trend Shifts


My next gig will be on 8th February. However, this time things are going to be slightly different for BIGScribe, I will not be speaking but I will be emceeing the event.

You can get more details on the events here :

http://www.bigscribe.com/macro/

As I get to develop a new skill in emceeing an event, I will not just be introducing the speakers and wishing all participants a safe journey home. Instead, one of things I will be doing is to build a framework around the two speeches and address questions that investors would want answered so that they can profit from event. 

Another thing I would be doing on that day would be to conduct the Q&A panel which will occur after the talk.

So far, all I can share is that I have already mapped out the possible local moves a retail can make to respond to macroeconomic events using SGX counters.

Depending on what the speakers will say, expect at least a couple slides where I will complement the information with some research of my own.

With any luck, there might even be some trash-talking from me on that day.

Anyway, do sign up for this talk, it should be fun and I might turn up the heat on the speakers on that day !

See you there.