Saturday, February 22, 2025

Three businesses getting disrupted right now.


Every time a semester winds down, I take stock of possible futures and think about the possibility of getting into new businesses with the skills I have developed. As it is too early to discuss the plans I hatched, I'd like to speak briefly about three businesses being massively disrupted.

a) Cinema business

Last year, when I figured out that Cathay Cinemas was not filming Deadpool and Wolverine, I knew that something was up. So, I was unsurprised that Cathay would have to shut down a few outlets, with Westmall Bukit Batok being the latest casualty. I doubt the issue is limited to just Cathay cinemas. 

Why does Gen Z or Gen Alpha need to visit a cinema when they can just watch a movie on Netflix after waiting for a while. Another issue is that recent superhero movies that consistently draw crowds are no longer as consistent as before, with Captain America drawing primarily a neutral reaction from audiences. 

I will continue to visit cinemas, but I will probably watch more Chinese movies in 2025 than Hollywood fare. 

b) Nightlife business

You have to admire Gen Z for figuring out how unwise drinking in the evenings is. 

I do engage in nightlife, but I'm a horrible customer; after paying a cover charge, I drink two bottles of soda water before hogging the Jap karaoke machine for the next 3 hours. What's recently new is that transport via taxi home is so expensive, it is cheaper to skedaddle home at 11.30pm, so there's public transport.

If everybody thinks like this, the nightlife scene is doomed, and we will see many watering holes leaving the market. If Singapore loses its vibrant nightlife, it will affect our tourism industry.

I hope it is not too late to lower alcohol taxes; I know of down-to-earth proprietors who do such work to put food on the table, and they are twice damned due to liquor taxes, and CDC vouchers cannot be spent in their establishments. 

c) Books

Of the three businesses, this one hurts me the most. I went to Kino today to observe the number of shelves vacated for a new cafe. The book space given up was quite significant, and even the finance and investment section now seemed much more minor. 

The situation in Singapore is that there aren't a lot of bookstores left to close down. The curation of bookstore shelves expands the selection of books I buy every month, although I buy a significant amount of physical and e-books every month. Game stores and bookstores are also great places to meet new friends - I would chat with anyone to find out what genres they like reading. 

The issue is that Ngee Ann City does not need a new cafe, given that there's a Paul and Killiney Kopitiam there. Still, I'm open-minded about whether Kinokuniya will build a cafe as a social space for book lovers. 

Book lovers must prepare for the eventuality that major bookstores like Kinokuniya may leave the CBD area and flee to the suburbs. In the worst case, you may even need to go to JB Tsutaya Books if you miss shopping for books in a big store. 

The $100 culture vouchers should be useable for locally published works, but most folks will buy assessment books with them. 

As my generation gets older, we would have to accept that the businesses we love will eventually come to an end. Gamers my age have seen the heartbreaking loss of Leisure Craft, Comics Mart and Borders. While many of these businesses are retail outlets where we buy stuff, these shops are also social spaces. 

I hope that in the grander scheme of things, the younger generation will have newer spaces to mingle and trade with each other.  

Saturday, February 15, 2025

Happy Valentine's Day ! Keep working on yourself, ok ?


Sometimes, I ask myself why I keep doing Valentine's Day articles. Is it because some of my readers actually enjoy reading it?

So this year's Valentine's Day is a lot more challenging for me as I help my mum get used to living with us, so my day is filled with managing her medical appointments and preparing her medications. Simultaneously, I'm also adjusting my social life to this new reality, getting out and socialising only after I no longer have errands to run for my family. 

On Valentine's Day, the sadistic folks running this AI/Data Science training program sent me two assessment requests on Friday. I spent an hour taking an impromptu data science test, which was OK. The software engineering aptitude test would be a cakewalk, except I ended up taking one of the most complicated tests I had ever taken in my whole life. It was 20 questions for an hour, and interpreting a question alone could take up to 5 minutes. I ended up completing only 12 / 20 questions.

I came off with some newfound respect for professional conversion plans. If we want to stop looking at paper qualifications, companies need tough exams to determine who gets the job interview, and there's no better way than to not let anyone prepare for these tests. 

But that was not the end of my ordeal. I had to walk my students through a Tort Law exam and do the exam myself, as no one was willing to give me an answer key. The good thing about trying an exam that your students need to take is that it can uncover challenging issues that need deeper thinking, and I have to deal directly with issues like time management.

Only after everything was over could I contemplate what to write about for this year's Valentine's Day.

I don't have much to work with other than my observation that Valentine's Day is very low-key in polytechnics. There were some flower booths, but only the girls seemed interested. Guys avoided those places because they might have to pay for stuff. During my time in JC, there were loud song dedications to our various crushes and a great time to indulge in relationship scandals - which I enjoyed deeply.

Another piece of news is this one that went viral after a guy paid over a five-digit sum to a Vietnamese Bridal agency but could not get a Vietnamese wife. The agency owner argued that he vacillated most of the time and wasted much of the agency's time. The amount he spent on the agency could have at least gotten himself 200 shares of DBS, which is declaring bumper dividends this year. 

The common thread of these stories is why even bother expending so much energy on Valentine's Day when you can just keep working on yourself. 

Until my mum's hospitalization, I hung out at a clean Japanese K-lounge, which was way cheaper than places like Cash Studio. The owners are businesswomen who run clean businesses and just chat with clients. It would be nice if you could provide conversation to young single men. No specialised skill is needed - you just need compassion and empathy. I told the proprietor that they are in the therapy business - they can say common sense stuff that sometimes friends and family may not want to say to a guy.

In these establishments, I noticed a lot of young men complaining about singlehood. But I suspect they are not doing the right things - they like to fuss over young women, spend money on them, and turn into simps, but they don't seem to be getting any results. 

So, that leaves us with the problem of defining what it means to keep working on yourself?

It is to improve parts of our lives that are not directly about finding a mate.

Going to a gym and sculpting your body to look good to a mate is not working on yourself. But it might be if you build muscle to improve your health and extend your life. The two workouts differ from those of a physical training expert - one workout will enable you to wrestle a bear, and the other will attract bears to you.

Reading for self-improvement is another area, but it's more complicated as women put a decent premium on well-read guys.

Building up an investment portfolio is also an area where working on yourself, even if it's just to ensure that you can pay for food and transport without using your salary, will push up your ranks in attractiveness. 

Like the guys in Poly, folks are sensing that male attractiveness is status-based, and we guys are rated in a curve against other guys. So, instead of signalling our attractiveness with inconsequential gifts, it's better to work on ourselves and build up our status to make a better play for a mate in the future.

So this year, for Valentine's Day, my message is to work on yourself. 


Saturday, February 08, 2025

Do you plan for higher taxes in the future?


If you read books by US financial planners, you will find a massive gap in financial planning skills between local and overseas. My general impression is that books from the US can be pretty technical, and a lot of it goes into details like tax planning and coping with their social security systems. In contrast, Singapore financial planning books are clearly written by commissioned salesmen. If you compare the font size alone, you will conclude that our local sales folks have very little to say.

I actually blame the folks who set the CMFAS papers here. Those who take the paper can develop a reasonably deep understanding of a complex financial product like an Accumulator. Still, they don't examine candidates on concepts like standard deviation, much less create a sense of terms like skew and kurtosis.  

The Guru Gap goes way deeper than what local experts do when it comes to tax planning. In the US, it's not enough to avoid taxes via legal means; retirement planning based on the safe rate of return should also account for future taxes. This is actually quite prudent and logical in the US because financial planners believe that the US government's fiscal spending is not sustainable, and everyone needs to anticipate higher taxes on dividends and capital gains in the future.

So, my thought experiment for readers is to ask themselves this question : How will Singaporeans be taxed decades down the road when its time to retire and start spending our CPF-Life money ?

I'm going to attempt to answer the question here, but do chip and share your views because I don't think I have any expertise beyond the readers of this blog :

a) Income Taxes might actually drop

For a start, I don't think our government, with a budget surplus every election term, would want to penalise folks who put in a hard day's work in this country. So, the worst-case scenario is to maybe introduce a new tax bracket of 24% above an income over $640,000. And this is not done to balance our books; it is done to make society more equal. 

In fact, I think the non-tax bracket should be raised to $30,000 because starting salaries are so much higher today that we should be giving lower-income folks a bigger break.

Will this affect financial planning for retirees? That is unlikely, but if I'm right, you can put more money into SRS so that you can withdraw larger sums when you reach 63 years of age.

b) Wealth taxes

Singapore is a wealth hub, so taxing Singaporeans over their wealth is tantamount to killing our golden goose, but the government has an alternative to wealth taxes in the form of property taxation. Wealth taxes are popular and potentially can create a more equal society. As land is scarce, Singaporeans will happily tolerate a higher property tax provided that the taxes are small compared to the increase in the value of their property. But property taxes are extremely unpopular for folks who are asset rich and cash poor, like my family before I showed my dad how to invest for dividends.

I predict that the best mechanism for property taxation is to just elevate the Annual Value for each property. And bigger punishment will be confined to folks who own non-owner occupied houses. 

I project giving up 2 months of rent to tax authorities every year for folks who own a second residential property.

c) Investment taxation

Although it might sound self-serving, I doubt the government will not touch capital taxes or dividends as our stock market is not booming as much as our property markets. However, one area we need to be constantly vigilant about is the tax-haven status of REITs. Every five years, the government will need to review whether REITs that give out 90% of income as dividends can do so tax free. The next review is 2025.

If the review concludes that this tax status will end, REITs will then be subject to 17% corporate taxation - that is one piece of bad news. The second risk is that REITs will no longer be required to give out 90% of their collections, so some REITs will start to retain more of their earnings resulting in a bigger hit to your DPU. Done abruptly, this will tank the REITs markets for sure and destroy the many years we've spent to build out our hub status. 

Imagine losing 20-25% of dividend payouts if this occurs. 

(This has always been one of my ERM training slides although I never want it come true.)

Financial planners and bank relationship managers will be so happy if this occurs, because it means the end of many FIRE journeys. I doubt anyone will do professional financial planning like this, so please diversify your assets betweens banks, REITs, business trusts and blue chip businesses. 

d) GST

I actually believe that the government is not done even after raising GST to 9% and giving out vouchers to the poor to offset a drop in their standard of living. There is a certain savage beauty of GST in that it will hit anyone who buys something, as even a tutor who fakes his income tax statement still needs to pay 9% when he buys something from NTUC Fairprice. A small increase is also extremely consequential and can fund so many more social initiatives. We've also invested in an entire architecture of CDC vouchers to surgically target the recipients of future welfare schemes.

So i think a savvy financial planner should factor for at least a 10% GST in the future with a corresponding increase in the cost of living for a 65 year old.

Of course, as my readers are smart, they are free to have a different projection about future taxes, but I hope it impresses on everyone that projecting higher taxes in the future should be something a true blue financial advisor will do, but sadly why should they? 

They are just people licensed to sell you more financial products.

Friday, January 31, 2025

Happy Chinese New Year of the Snake !


I've spent most of my Chinese New Year accompanying my mother at Woodlands Health, and I'm happy to say that she has recovered most of her speech. She still needs physiotherapy and may be moved to a community hospital for more intensive rehab. Consequently, this is the most peaceful CNY I have ever had as I converted the ward into my tiny office space to work on a new project, mark students' scripts, and prepare for my next round of previews next week.

As it is traditional and very apt to talk about metaphysics every Chinese New Year, my Chinese horoscope reading has been spot on. 

For folks wondering why this blog becomes superstitious every New Year, I have my own philosophy regarding Bazi and the Stem and Branch system of the Chinese zodiac. The first concerns the limitations of my mathematical models - even if I can predict a crash based on financial metrics, too much hinges on black swan events that economic models cannot predict, like the pandemic. I have never met a Bazi master who recommends forgoing birth control, for example. Secondly, zodiac readings are almost universally conservative and never encourage making bad life choices. Finally, I prefer Joey Yap, who is very English-educated and likes to put a positive twist on my reading even though everyone's favourite Ch 8 horoscope uncle has rarely given me anything good for the past 5 years. 

In other words, I don't treat Chinese metaphysics any differently from other astrological models like the MBTI, DISC, Emergenetics or the Enneagram. I use all of it to guide my life and deal with the uncertainty that risk models cannot capture. 

The new year has boosted my finances, with almost all my different strategies posting slight returns and the valuation on my real estate showing the most significant gains. Still, all these came with a personal price, as in addition to my mum's fall, my kids have fallen sick. All this is reflected by the Tiger Horoscope, as according to Joey Yap, we have six inauspicious stars against two excellent ones. 

So career and money-wise I should do quite well this year of the Snake, but I will face many personal and emotional challenges. One amusing star I need to deal with is aptly called the Curled Tongue, and the year is inundated with lousy luck involving my adult students. One entitled boomer has constantly disrupted my lessons and insisted that the syllabus and training materials reflect his expertise as an ACTA-trained professional - I'm preparing for the worst before the feedback report returns this semester. Another thuggish student with anger management issues has written to me stridently demanding I recommend him for the SUSS law program - I have relegated his email to my spam folder.

For folks who know my story, Chinese metaphysics led me to collaborate with Dr Wealth because I was told that I have an outstanding balance of elements except the ability to seek help from others, which has been holding me back my whole life. This year, I started working with a new partner to generate shorter (and cheaper) online training courses to drive more traffic to my main course previews. While I have grave doubts that this is monetizable, I'm impressed by the technical and influencer training I cannot replicate with a Skillfutures course.

This is yet another decision that came about purely because of Chinese metaphysics.

The background is that I was not really prepared to do something new or aggressive this year. Especially since my potential partner has a different but admirable goal: geo-arbitrage, where I prefer to work with local partners. Furthermore, because of capacity issues, I blew off another guy (a loyal reader of this blog) last year because I could not adequately quantify the value of the effort.

What changed the game was the advice I got for the Tigers in 2025. We're overwhelmed with unlucky stars in 2025, but we can turn the tide proactively and allow benefactors to assist us. This is one of the components of Chinese horoscopes that I like. If it comes out from a Bazi's expert's mouth, we might ignore them, but CEOs will pay millions if the same stuff comes from some Mckinsey consultant. 

Anyway, my latest partner is an ISTJ. If an ENTJ and ISTJ can't make money on a project together, they must be mentally ill, extremely unlucky, or both.

I've already put in a decent amount of CAPEX that would enhance my preview materials for ERM. 

I will announce this on my blog once we are ready to promote the product.


Monday, January 20, 2025

Why an 8% safe rate of return can be better than a 4% one ?


First, a shout-out to friends and fans who wished my mum a speedy recovery. Yes, she is well on the road to getting better. As for me, I've settled into a routine at the hospital, which has allowed me to read and blog more. 

Today, I will talk about this peculiar book called The Guru Gap by David Mcknight, which discusses fairly technical personal finance topics for US readers and compares the central ideas the different gurus have.

One interesting discussion is an exciting take on the safe withdrawal rate that had been discussed to death in local forums. Apparently, many professional advisors in the US are quite cheesed with Dave Ramsey for suggesting an 8% SWR instead of a 4% one, even though the 4% has been backtested and Monte Carlo simulated to death.

Strangely, the book has succeeded in a reasonably robust defence of the 8% SWR, which may drive Investment Moats into apoplexy. 

The idea is that Dave Ramsey, a popular finance guru in the US, is very aware of the limitations of spending 8% of a person's portfolio every year. At best, the odds of surviving 30 years of expenditure without work are slim. Still, from the US context, it was argued that if you tell an average person that he can only spend 4% of his savings every year, he will be so discouraged that he will not even bother to do anything about financial planning in the first place. So, the viability of the 8% withdrawal rule is a workable lie for folks to get started and shift to a lower withdrawal rate once savings hit a critical point.

Beyond this argument, the book's value shines out when the discussion begins about how an 8% withdrawal portfolio can actually function. This is, sadly, not totally within a credible discussion in Singapore. However, a commissioned financial advisor with some brains might consider reading this book and shoe-horning it into the local context.

The first obvious idea is to employ an annuity to gain lifetime payouts. Annuities bought from the private sector may not pay for life and can be expensive. Instead, we are luckier than Americans because we have CPF-Life. Locally, if we have CPF-Life at the ERS level, spending down 8% of our portfolio is credible as CPF-Life at 4xBRS can generate more income than a 65-year-old needs to have a basic standard of living.

The second idea (which I do not understand well) is that the book also recommends having a volatility shield to spend down on recession to complement an 8% SWR portfolio. If you have a volatility shield with 8 years of living expenses, you can spend 8% with high odds of surviving the next 30 years. But what is interesting about the author's recommendation to invest in the shield is that it will give a warm fuzzy feeling to the commissioned-based FAs who read my blog.

The proposed approach will enrich an FA because it should be invested in an Indexed Universal Life product. The claim is that, after fees, such an instrument can still grow by 5-7%. I leave further discussions to the MDRT and CFP people who read this, but I was not pleased to know that buying an IUL is basically buying an ILP + Whole Life policy.

While the ideas in this book are a treasure trove of ideas that can be adapted to the local context, there isn't a need to deviate from the wisdom of local investors.
  • We use CPF-Life to generate a bare-bones existence even at the FRS level. About $1,100 in today's dollars under the standard plan.
  • We use a dividends portfolio and an SWR equal to the current yield to cover the shortfall, which is about $400-$600 monthly compared to CPF-Life.
  • Our residential home is a source of capital gains and room rentals, covering our bequest motive. 
  • Our kids, if raised correctly, are annuities of last resort.
Sometimes, conventional ideas are great!


Saturday, January 18, 2025

Becoming.a Main Street Millionaire


I’m blogging from Woodland’s Health, a hospital in the North where my mum is recovering from a bleeding in the brain after a nasty fall last Friday. At the moment she is out of ICU and the acute ward and recovering from the general ward. Consequently, I was distraught for the past 4 days, but I’ve slowly incorporated this to my daily routine in hospital, helping out as much as I can and trying my best to see whether I can squeeze some productivity out of this. 

One of the side effects of being in hospital for the greater part of the day is that I can read peacefully, so I am actually faster at preparing my course materials and I can now wholeheartedly recommend a good book for readers of my blog.

One of the arguments going on in the FIRE movement are the latest salvo of brickbats thrown at us. Somer folks think that retirement should be postponed to preserve social capital, others claim that working may also mean that there is no genuine security that comes from the investment portfolio. In both cases, I wanted to jump into the fray, but I don’t think there will ever be an end to these skirmishes. FIRE’s ability to attract detractors is a testament to its strength.

Instead, I want to invite readers to consider the alternative to FIRE in the form of a business acquisition. In this book, author Codie Sanchez suggests that a good life can come from taking over a business from a retiree and then finding ways to automate and digitize the operations. While I do not have experience doing this, my brother in law is an excellent example of doing extremely well in life following this play book and he owns factories all over the ASEAN region.

There are two extremely valuable gems on this method of wealth generation.

The first point is to look for businesses that are immune to market cycles and easy to operate, then offer to pay about 2-5 PE ratio for such businesses, finding ways to achieve vendor financing along the way. This is not easy to do in Singapore as you will then be limited to businesses like laundromats and Gachapon machines. I find this section an absolute gem then because I can then use a stock screening software to find stocks trading below 5 PE and ample free cash flow and seeing whether I can buy cheap businesses from SGX. I’m going to keep mum on my screen and the results, but I have at least one investment idea from this book.

The second point is the idea of the technology stock for SMEs. Modern small businesses need not be powered by employees but active automation can be done with an array of software as a service solutions. For example, for employee commmunications, SMEs can use Slack. For documentation and SOP, can use Notion. For recording of screens training, can use Loom. This section alone justifies paying for the full cost of the book, but I needed to consult my mastermind group of young influencers to translate into software we actually use in Singapore. I have to admit that I’m actually very enthused to bring this technology stacks into Polytechnic training as this is the kind industry streetwise diploma holders need to compete in this world. 

For one thing, I don’t believe that a person’s ambition dies just because he has completed the FIRE movement. I’ve been checking out business franchises, and readers and folks who listen to my podcasts have been directed to looks at entrepreneurship to complement the FIRE journey. Buying a consistent business is a very different skill set from investing. If you find the right business, you often do not pay more than 4-5 PE for it and if you pick well, it can pay for an operator and leave plenty of “almost-passive” income for you. However, if you backtest a SGX strategy that has a PE below 5 and dividends above 3%, you would have lost money of the past 10 years. 

I hope readers will find a way to read this book and even find a way to give its ideas a spin.

Do keep me in the loop. 

Wednesday, January 15, 2025

Dealing with a crisis - no updates on this blog for a while

 Last weekend, I found my mum looking confused and unable to form coherent sentences and I ended up getting an ambulance to send her to a hospital as it looked like a stroke. For the last few days, I’ve been shuttling to and fro from the hospital.

Just yesterday my mum transitioned from the ICU to an ordinary ward and I can breathe a little easy, but the road to recovery is going to be very long as she’s lost the ability to speak.

I’m also sitting next to her while I’m hammering out this article. 

All I can say is that I’m grateful for a few things:

  • I’m glad to be at Woodlands Health where I can do some work and shuttle home over one stop where I can bring what my mum needs from the house. There’s even a new bus 967 that lets me do this.
  • We’re financially ready for a catastrophic event to occur, although the hospital has not even broached the subject of Medisave use to me yet. They seem to focus on patient first before payment. 
  • Compared to other stroke symptoms, my mum’s were light. No paralysis of half the body and I can play charades with her to guess what she wants. My mum even had the presence of mind to get me to prepare her medical prescription to be shared with the hospital. 

For the past three days, my mind has not been calm to say the least. I suspect the weakest link in dealing with this event is me. I was still able to do my preview last night and have two days of lessons starting this evening. 

Financial preparation aside, I’ve learnt how vulnerable I am, it was hard to be along in a room as I’ll begin ruminating about what i could have done better as a son. There are also a lot of unknowns like how would long term care look like, and what my options are, so I managed to get a social worker send me brochures  for me to meditate upon. 

Everything being said, I have friends who have gone through this themselves and they are actively helping me cope. I also am lucky have a friend who was able to meet me for breakfast to just cheer me up before I visited the hospital. Relatives from across the causeway are providing heavy duty professional medical advice, going as far as to read scans and share with me what the issue might be. 

Finally, I’m super grateful that my wife and kids can hold the fort. Almost everyone has some light flu symptoms. Hope its not HMPV.

Note : I might disengage from some chattier groups for now. It’s nothing personal.


Sunday, January 05, 2025

Is it time to make peace with commissioned financial advisors?


AS 2025 rolls by, one of my priorities is to come up with new slides that are more relevant to the marketing of my Early Retirement Masterclass, and one of my priorities is to see whether the messaging about commissioned financial advisors remains appropriate to modern audiences. 

There are objective reasons to do so on the first examination because FAs seem less pushy these days. The booths where agents look for potential clients are quieter, and I definitely do not see LED balloons being used to lure children anymore. Furthermore, we're not seeing FAs using FB groups like Seedly to get new businesses; the pushy ones that were around before the pandemic have mostly lost their licenses to practice. At the ground level, ERM previews used to attract a lot of FAs who would try to troll me when I revealed some harrowing truths about their profession, but I've not had trolls for quite a while. 

Maybe to help me, readers might wish to share their personal experiences - do they still get FAs asking for a date on their dating app? Are their events organizers FAs in disguise? These are problems folks were telling me in the past. 

So I tried to do further research in this issue.

So as it turns out, reported statistics do not paint a nice picture in the industry. According to FIDREC, on 2023/2024, claims have gone up 32% to 2,894. Life and composite insurers attracted 387 claims and license financial advisors and insurance brokers got 61 claims. 

To decide whether these numbers are big or small, just remember that CASE wants MAS to regulate financial influencers even though they are getting 5-6 complaints a year, which makes me wonder who is really pulling the strings in this issue? 

Next, I should use my legal training to come up with another objective approach is to simply let the reader or attendee decide and just draw my materials from court judgments, which is open to examination by the public. I've made a new slide to be presented on my new preview that sheds some wisdom for folks who want to know what can go wrong when they receive advise from the wrong party.

Let me share my teaser slide below.


In case folks are wonder, this case is now taught to Polytechnic students in Singapore. I have a special sort of interest in this case because,  according to what I read, I was surprised that my pupil master was instrumental in winning this case and crafting the arguments for the appellant. 

Which means that in some alternate universe where I survived my pupillage and decided to do pursue a legal career instead of taking up Dr. Wealth's suggestion to teach Early Retirement, I would have been a saviour of this group of Financial Advisors today instead of being a vocal critic. 

So is it time to make peace with commissioned financial advisors?

I think I need to tone down the rhetoric. How convincing the rhetoric is depends on how annoying the industry is and, save just few folks who lost their licenses have found themselves teaching other FAs, my case no longer rests on a solid foundation of dissatisfaction from the public. 

And it's not necessary anymore - even when I polled my teenage students and asked them who would invite them out for lunch for a catch up after graduation, they would laugh and say that it's highly likely to be a classmate who became an insurance salesman. My students are very streetwise.

Instead, I will use statistics from FIDREC and a wonderful selection of local court judgments to let the attendee decide what to conclude regarding the industry and whether there is a need to build up their own financial proficiency and not rely on others. 

For lasting peace, maybe you should focus on Gaza or the Ukraine for now.


Tuesday, December 31, 2024

Did you make any resolutions for this year ?


I've only recently learned how fast time flies for middle-aged folks. The science behind this is that our brain neurons fire much slower, so everything seems to move faster. I've started the habit of stopping myself from reading "useful" books every birthday month to at least catch up with fantasy writing and gaming trends, but this year, I could not read very much. 

For Japanese Literature, I read What You Are Looking For in the Library by Michiko Aoyama. It is a lovely, soothing book that discusses why people should read and how books can turn your life around. It should be given more attention in Singapore because adults read much less. The other book is Lantern of Lost Memories by Sanaka Hiiragi, which is not my style but forces us to ask questions about what day we would like to relive after we pass away.

This is the furthest I can go with serious literature. 

For fantasy literature, I finally started with the first book, Xenos of Eisenhorn Trilogy, by Dan Abnett, which is a page-turner and a great introduction to the Warhammer 40,000 universe. Then, I could cover 40% of the fourth book of Brandon Sanderson's Stormlight Archives, which feels more superhero than fantasy. Still, it's become compulsory reading for me lately as it spawned the most successful RPG kickstarted. 

Finally, I could complete just one large volume with games: Monster, Aliens and Holes of the Ground by Stu Horvath, which runs down different RPGs from the 1970s to 2010s. This is one crazy project that took a few weeks to complete.

That sums up my December, I could not binge-watch, and I now look forward to reading the more "useful" books again starting tomorrow. 

I was once again with a friend at his usual Japanese lounge and bar, and I was stunned when the hosts asked me what my resolutions were for 2025. I was so focused on processing what happened in 2024 that I forgot what I wanted in 2025. 

Last year, I did not dare to make any resolutions, but I hinted that I might start writing a new book or starting a content channel. Still, I did not do all that as my law lecturing workload increased by 300%, so I could be more over-employed as I juggled two freelance roles. The good thing coming out from all this was that 2023 bottomed out, and a quiet benefactor appeared in 2024 to make sure that, in the aggregate, I earned more than 2023 and may start paying taxes again in 2025 after a 4-year hiatus. The market performance, while muted, was still positive, but we will leave it to a Dr Wealth article I will have to start writing tomorrow. 

Overall, I ended 2024 in a slightly better state than 2023 - actually, 2024 was fun with class reunions and hanging out more with my secondary school and JC friends. Socially, my engagements have become more positive. Health-wise, there are no new health scares, and I've gotten used to my prism lenses. Juggling freelance work will never be as stable as regular employment or receiving dividends, so my only resolve is to manage these priorities well and not drop the ball in 2025.

I'm obviously looking at new collaborations. I'm also looking carefully at the kinds of professional conversion plans launched in 2025 and will not hesitate to pick up a considerable, solid skill like AI software development or even quantum computing. But these are iffy and random options, much like my failed attempt to become a professional GM. 

However, a post-financial independent life needs to have a string of beautiful failures and audacious moves because the consequences of failures are so small. Still, the impact on the ego continues to keep one humble.


Saturday, December 28, 2024

Harsh Truths about Masters Degrees and the folks who have them.


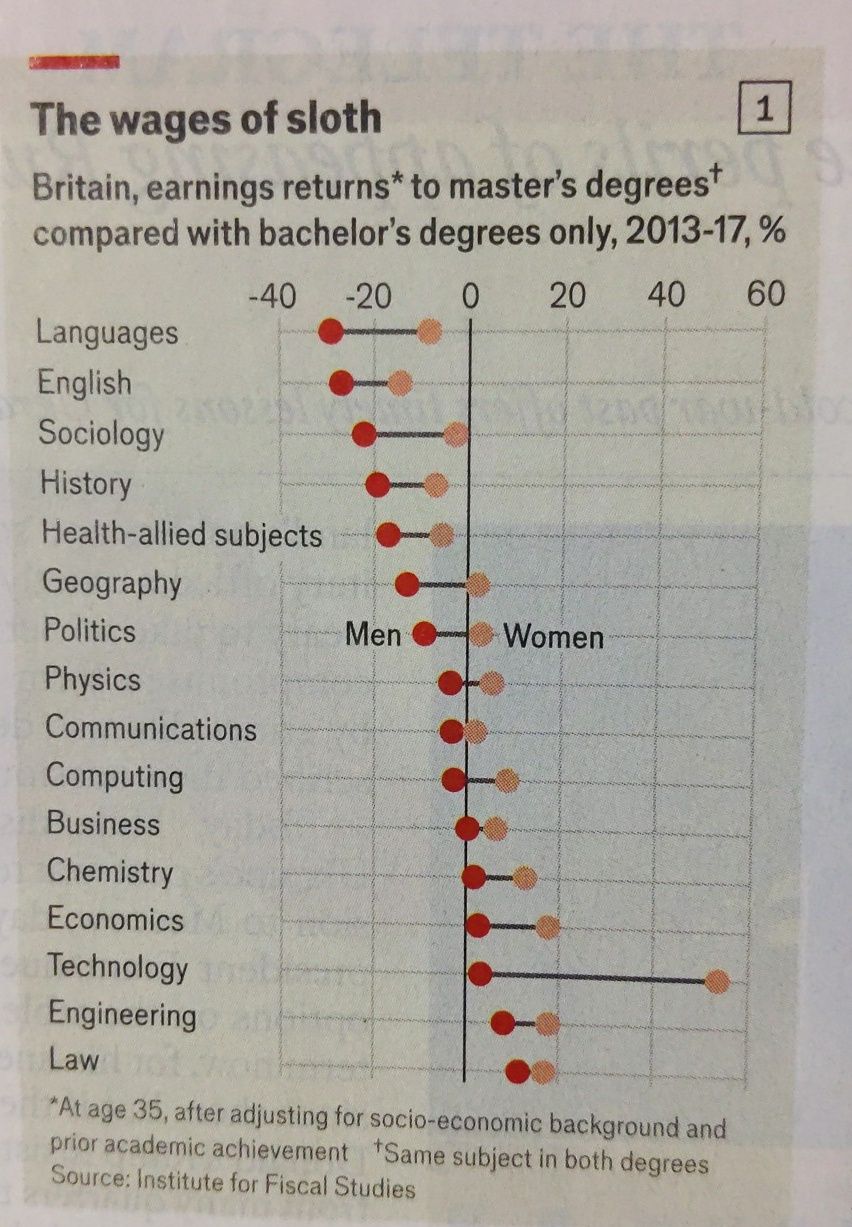
About 3 weeks ago, The Economist published some earnings returns to folks with Master's degrees and measured the value added of these qualifications over those with bachelor's degrees. They found that after adjusting for social and economic status and previous job roles, these degrees do not add much value to the person taking it. 

But the actual data is a lot more damning - folks who had advanced degrees in languages, sociology, English and history actually earned significantly less than those who only had bachelor's degrees, which sort of makes you wonder what kind of folks peddle these programs. If your only career recourse after studying for an advanced degree is to teach the same subject in another institution, then you are no different from someone who sells MLM. You might be part of a humanities Pyramid scheme.

Naturally, the response to the Economist was quick and aggressive, with many academics writing articles to defend their product and saying things like an ROI should not be the primary reason why people should spend more time in school. Ideally, people should be driven by their love for learning. Of course, none of them addressed the elephant in the room - if you have a Master's degree in English or Languages, it would destroy more than 20% of your earning returns!

Another critical data point is why women benefit much more from a Master's degree. The Economist explains that advanced degrees mitigate the motherhood penalty, and women with these degrees continue to pour a lot of work into their careers. Sadly, no troll jumped on this point - men who are about to date highly qualified women need to be put on notice that they will commit less to their families. It's a valid conclusion as well that the manosphere should jump on!

Of course, MBAs are right in the middle of the pack; in the Economist article, MBAs generally do not add any value, but the article hints that very prestigious MBAs tend to have high ROIs. And I'm happy that the Business Times today had an excellent article to fill out the gaps for MBA programs.


The numbers reflect well for the MBA programs - yes, even those for NUS and SMU which are not precisely programs you attend for a higher income, but something you need to have an alternative other than the public sector. When I was studying for my Master's in Finance at NUS, the MBA students tended to be civil servants trying to find alternative employment, and more often than not, a local MBA fulfils that objective for them.

Actually, I did hunt for a Masters program in my mid-20s. My GMAT score was 720 with a 6/6 for the essay component - it was enough to get into an MBA program, but probably not the best program on that chart, so instead, I went after the CFA and paid cheap tuition for it - my MSc in Applied Finance cost to be $10k in total. All I paid was the CFA exam and membership fees. I've always been curious what the ROI for my CFA was, given that I never joined the finance industry before Dr Wealth and brought in a 5 figure passive income a month today - would I have the courage to move my funds from unit trusts to manage my own dividend portfolio if I hadn't witnessed how dumb, mathematically inept ( especially those who fail CFA level 2, you know who you are ) and self-serving finance folks can get?

Ok, so now's the hard part, what can we conclude from this data:

a) If you get a local tech or engineering Master, you should seek an overseas posting.

I don't think the situation has changed much for folks who study for a Master's in Computing or Engineering. The range of jobs is not particularly good, so you are better off going off to Silicon Valley and joining a startup that values your skills. I don't think the ROI for a Tech master in Singapore matches the number in the Economist article.

This has not changed for many years; if you are a computing or engineering graduate of any level, you will always be better off working in the United States to build up your experience. The stock options alone might make a millionaire at a very young age.

b) An advanced degree's primary value is in its signalling effect.

I suspect that you are better off signing up for a course I teach at the Polytechnic if you want to pick up actionable and practical skills, I teach Tort Law and Legal Technology, and sometimes I will make you assemble a PDF document using different free software found on the web or employ ChatGPT to analyse a contract. Amazingly, I also teach office politics and how to stop a dagger from being shoved up your back. Also, the course is almost free, thanks to subsidies. 

But that's not what most readers of this blog want. 

For a Master's degree to have a signalling effect, what is being taught is secondary. Harvard has an excellent case study approach, which makes it the Rolls Royce of MBAs, but the real value of a Harvard MBA comes from the question of who is excluded from the program - which is almost the majority of all applicants. By the time you enter Harvard, you are already a superstar and will build up your social capital working alongside other superstars.
  
c) Can a bad master's degree tar your resume?

You'll only read inconvenient truths on this blog, and I doubt you'll find anything in the mainstream press that will publish stuff like this.

Suppose we believe that some Master's degrees can add a lot of shine to your resume and raise your income. In that case, we have to accept that there is a possibility that some qualifications can reduce your employment outcome even though there's this belief that more learning should be a good thing. After all, we live in a world where a guy can marked down on a dating app if he loves anime or poses with a cat in his profile photo. 

For a while, we know the effect being a private university graduate has on your starting salaries. What if having some Masters degrees marks you as having a political orientation or a more hedonistic outlook? It's a stereotype, but some stereotypes are true. In many social sciences, academics are leaning to the far left. Why would a capitalistic and bottom-line oriented multinational company hire them?

Elon Musk tried to hint as such, saying that he prefers skilled tradesmen rather than those incremental political science types - which aligns with the data from The Economist.

d) A Master's degree may be useful in qualification laundering

Sometimes, I get readers stuck in a dead-end job because they have a private degree. In such a case, if they can get a Masters degree from NUS or NTU, it would take the focus away from their private degree when preparing for a job interview. This might be one of the rare and more practical reasons to pick a run-of-the-mill Masters from a local university.

I call this qualifications laundering; it's not a nice name. 

But I like it.

Anyway, I'll catch you guys again closer to the new year !


Wednesday, December 25, 2024

Finally hit my half century mark.


As I prepared for this post, I've just tried to contribute to my Medisave account on the CPF website, and I've been hitting a wall thanks to the dumbass Paylah limit DBS has put on me. Somehow, I can't figure out why I can't contribute to CPF via NETs. 

Anyway, I wanted to say a few words to my readers and well-wishers as I hit my 50th birthday today. 

The past 3 years have been peaceful but not precisely as prosperous as I wanted as interest rates began to rise and yield plays 
took a hit in the markets; nevertheless, I made some gains, mainly in the value of my real estate. As I've spent a lot of ink looking at the past, it is time to look at the future.

a) Options are now open for me to make as many changes to my career as possible.

As I've now balanced two part-time sources of earned income, I'm reaching a state of balance in my finances to accumulate enough to have a track record of income and a reasonable flow into CPF - which I lacked after FIRE. This is a humble amount, but it balances the risk if I ever need to refresh a home mortgage, and I can still put more money in my CPF to offset taxes and draw the 4% from my SA before it disappears at age 55. 

I can do more as I've gotten used to one rough day a week where I slog 13 hours and get myself used to the morning commute and dysfunctional work encounters. 

Like many Singaporeans, I'm looking at how I can monetise a full-time course to pick up some new skills and max out incentives to learn based on Skill Futures. At the top of my list are data analytics, AI, and even ACLP. However, I will be selective about these programs as I have time, money, and cognitive bandwidth. The skills I gain must be helpful in all work areas and make me more valuable to my business allies.

b) Investing in 2025 - All about high dividend SDRs

Many bloggers don't appreciate the hard work done by SGX this year for many local investors, as locals have been glued to the AI stocks in the US and enjoying the dizzying capital gains of 2024. 

I'm a contrarian, not too keen to push more funds into a market with PE ratios above 30. However, I have a successful momentum trading algorithm running, making some spare changes every month.

So, in 2025, I will ramp up some funds into the Thai and Hong Kong SDRs trading in SGX, with a significant position made to Ban of China. I'll be looking for high yields that feed directly to my bank account from CDP, with PTTEP being my next purchase candidate. 

I hope SGX will try to get more high-yielding SDRs into the exchanges, except for Malaysia, because I still remember CLOB.

Of course, as I pick a new focus, material in the ERM programme will also be refined in the same direction. I'm figuring out how to calculate the payout date for SDRs, as it will arrive later than for foreign investors. 

Do note that I've become more and more sleepy about my capital. Interest rates will likely stop ratcheting down in 2025, so perhaps things might be tad boring in 2025 for us yields investors. 

c) Social Life

It's good to pick up some gaming groups for a change, and I've become a casual player for one group who can play any game they want. Otherwise, being invited to an occasional meetup with readers and fellow gamers on this blog is excellent. If I sell more time in 2025, I may lose a few meetup opportunities, but it's okay to make my weekends valuable again. 

But my most tremendous pride is starting my son to paint Warhammer miniatures with me and play a few rounds of introductory skirmishes. 

d) Hobbies and games I will be playing

I'm slowly turning games agnostic. I will be focusing on Legend of the Five Rings as I've only managed to find someone to play the LCG with me after long years of collecting the game. I'm also hacking a Kill Team squad of Intercessor Marines just to fit in, which means more work to paint all those miniature games I have accumulated on my shelf. 

The policy is I'll play anything if there are slots available. With this in mind, I'm still collecting D&D books to read and will still find a way to play a game or two using the new ruleset.

Entertainment-wise, I don't need to binge-watch anymore; I've started watching Dandadan and Secret Level and might ditch my Disney subscription soon. It's infinitely better to read. Also, this holiday, I reacquainted myself with fantasy and hope to finish Brandon Sanderson's Stormligght Archives and the Warhammer Eisenhorn Trilogy. 

There are many ways to achieve flow, such as strategizing a deck for play or painting a miniature, but there are better ways to engage in the real world. I plan to build a new trend-following algorithm for the crypto markets before the New Year. 

There will still be plenty of time to think about the future. I've got one more round next week in 2025, and there's also Chinese New Year. 


Saturday, December 21, 2024

Letter to Batch 36 of the Early Retirement Masterclass


Dear Students of Batch 36,

It's been a great honour and privilege to conduct a 5-Day Early Retirement Workshop for you.

The markets are still experiencing a roller coaster ride after the conclusion of the US elections, and we are seeing some evaporation of previous gains as markets begin to digest what a Trump presidency might mean in 2025. In Singapore, banks advanced, and REITs retreated as there was this belief that Trump tariffs would generate inflation for the US economy. Interest rates continue to trend down, giving Singapore investors an extended bargaining period to collect high-yielding counters for a longer period.

The current yield of this portfolio is 7.35%. Once again, as the batch size remains small, we have created a very focused portfolio of 12 stocks, not counting Bank of China, as we welcome our first Singapore Depository Receipt (SDR) into the ERM portfolio. In future batches, we will gradually increase our exposure to high dividend-yielding SDRs, which will see at least one high dividend counter coming from Thailand in March 2025.

Also, for this batch of students, students employed ChatGPT on SUTL Enterprises, and an AI-generated analyst report is also attached to the materials herein. ChatGPT is getting better and better with each iteration, and it is our wish that we can decouple our program from analyst reports one day.

Lastly, I hope Batch 36 will participate actively in the FB group.

Hope to see you then!

Christopher Ng Wai Chung


Saturday, December 14, 2024

Are you part of the CDP Master Race ?


[ The concept of the CDP master race is inspired by the idea of the PC Master Race, gamers who game on their PC. It is not inspired by WW2 Germany. ]

For modern investors who are younger Millenials and Gen Z, there is no need to understand what the Central Depository or CDP is because modern brokerages that run on the custodian system are very competitive. Trading on an old-school broker usually costs $25 per trade, while online brokerages like Interactive brokers, if charged at all, can often execute for around $2. 

Despite cheaper trades available, I still prefer to park most of my net worth under CDP, and I imagine many older investors may also like it. 

Here are my reasons for doing so. 

a) Singapore Savings Bonds or SSBs

SSBs should still be the safest investment in Singapore. Based on what I know, the only way to buy them is that you will need a CDP account to do this. SSBs are the closest thing to investing in a risk-free rate, and this should be noticed if interest rates spike one day in the future.

b) Shareholder activism

Shareholders need to know what their companies are doing, and when you own shares in CDP, they are held under your name. You can join shareholder meetings and fight for scraps at the buffet table. Shareholder activism also means voting down ideas that you do not like. While this is nothing much for younger investors, it gives the retired elderly something to do - you can also meet other people.

c) Dividends on payable date

This is a massive deal for me. For a successful setup, dividends will arrive by 5.30pm in your local bank account on the payout date. The money will come even if you do not have a recognised degree, study in a neighbourhood school, or might lie in a hospital in a coma. For custodian accounts, they will show up the following day on your dashboard, and then you need to issue an instruction to pull the dividends into your bank account. 

This causes delays and is generally more active than people think passive investing should be.

d) Easier on your beneficiaries and gifting your children

When you pass on, knowing that the bulk of your funds are in CDP will make it easier for your trustee to handle the stocks. For my dad's case, I opened a joint CDP with my mum and then moved the stocks into this joint account at $10.70 per counter. When my kids reach 18, I intend to pass on some blue chip counters while I am still alive.

For folks with online brokers, do realise that chasing freebies will result in many brokerage accounts that can give your trustee a logistical headache trying to distribute your investments. I've not done such cases, but I suspect if it is an online brokerage, it may be better to sell everything and then distribute the cash to all beneficiaries. (Ensure your kids know how many investment accounts and which brokers you have.)

Bonus: Not so much about CDP but the Supplementary Retirement Scheme or SRS

By opening an SRS account with a bank, you can set aside sums up to $15,300 to invest in the local stock market and reduce your personal income taxes the following year. These can be huge savings for folks in the high-income bracket. Amounts saved in SRS can be invested into the local stock market until you are about 63 years old. You must require a traditional brokerage account to trade stocks by drawing sums locked in the SRS account. A correct setup will give you a conventional brokerage that uses funds in your bank account or SRS at the same time.

Of course, employing CDP with a conventional brokerage is only practical in some cases.

As traditional brokerages charge more for each trade, you may only wish to use stocks you intend to buy and hold. Bluechips like DBS and low beta REITs like Fraser's Centrepoint Trust and Netlink Trust rarely make sense in high turnover portfolios, so they naturally would make a great fit with CDP. I generally employ high dividends and low beta in my core dividend-paying portfolio in CDP.

Online brokers are better for high-turnover investments. My algorithm-driven trades are all done exclusively via IBKR.

Share this article, as CDP gets little praise on social media. I think all serious retail investors should have one account.

Sunday, December 08, 2024

Curse of the Hummingbird


This article arose from a series of discussions in the SGFI telegram group. I thought I'd share some deeper thoughts on it, as it is relevant to self-improvement and investment.

The person who started the conversation spoke about the advantages of being a jackhammer. A jackhammer has a narrow focus on hobbies; all they can do is focus on one thing and happily lead their lives. The opposite of the jackhammer is a hummingbird—something that flits from flower to flower without ever discovering what they are meant to do. The original inventor of the concept believed that the world needed more hummingbirds because hummingbirds can bring a cross-pollination of ideas and create innovative breakthroughs.

You will find many more metaphors in business literature, such as the hedgehog and the fox. 

As far as my own analysis goes, folks with an S in the MBTI, like the dreaded anal ISTJ, are jackhammers and do pretty well in Singapore, especially the government. In contrast, folks with an N tend to be hummingbirds, as they have big ideas and can apply mental models across domains. I tested ESTJ in my teens and ran with it throughout my engineering career. Still, once I started to pick up investing, the S had no choice but to give way to a more N or intuitive approach towards problems as I began to see investing as a form of liberal art where analysis can come from multiple angles. I was influenced by an old book called Latticeworks by Robert Hagstrom in the early 2000s. 

Are there investing styles for jackhammers? Indeed, using broad index ETFs to construct a 60/40 - VT/BNDW portfolio can be very effective because it can compound between 6-8% over multiple decades. Then, it's just researching ways to reduce expenses and finding more ways to optimise your day job to accelerate wealth creation. Picking this up remains the best defence against financial advisors and paying high commissions to get your money to work for you in the markets,

Dividend investing could be slightly more sophisticated, so it can be suitable for jackhammers. Just target sustainable yields between 5-7%, then stubbornly build up a portfolio of local stocks in a CDP account to reap hundreds of paychecks yearly. It's more complex than 60/40, but the folks who do this are so loyal to this approach that influencers still get cheap eyeballs by provoking and disrespecting "dangerous" dividend investors.

The transition from jackhammer to hummingbirds starts when you become dissatisfied with the Sharpe ratios you are getting. This happens when you interrogate your data and find factors that outperform. Factor investing is very rewarding for hummingbirds because when you see a new factor that works, it is interesting to explain why. Like why do low Beta strategies work? Do people take stock bets based on excitement, so boring stocks are cheaper?  

Technical analysis and charts take hummingbirds slightly further. Some folks love reading tea leaves for different patterns to emerge. I enjoy coding to discover trending ETFs and buy them for better results - that's a very technical investing approach. I've finally moved all my Terra coins into ETH, and I'm developing a momentum-driven algorithm to see whether I can juice my cryptocurrency portfolio in Binance.

However, some strategies only appeal to extreme hummingbirds, and I dislike them. I don't like derivatives and zero-sum games, so sacrificing an upside to juice dividends using covered call strategies is just there to make some folks feel really smart. I'm sure they can make money, but I don't have the time for it. 

Maybe the solution is not to be dualistic about the jackhammer-hummingbird divide.

Based on our personal resources, conscientiousness and intelligence, we have a pool of attention to devote to various interests. 

The jackhammer will narrowly allocate his attention and get deep into a few areas.
The hummingbird will speak thinly and have a passing interest in many fields.

However, many approaches need to be broader and more profound. 
  • One way to moderately go into two fields and synergistically use them at work. 
  • Another is to supplement a broad interest in many things with one narrower focus on one area you are passionate about.
There are several principles to guide us when determining to pick up a new area of interest:
  • If you decide to pick something, a hobby or a field like finance, the opportunity cost is not picking something else, like brewing hipster coffee or writing sonnets. 
  • If you keep focusing on one thing, the payoff may achieve diminishing returns. If you have a 6-7% dividend portfolio, and some folks are raving about dividend growth as a better approach, they might be correct, but how much better? Dividend yields are more visible, and dividend growth requires projecting into the future.
  • Some things have a J-curve. A project may generate negative returns and frustration but pay off later after you allocate more time and effort. A 1-month violin course is a bad idea. 
  • The amount of resources a person can allocate is limited by wealth and talent. Life is not fair.
Because SGFI groups have so many INTJs, it's normal to think that it's a curse to be a hummingbird, as INTJ's significant weakness is the inability to stick to a hobby. At the same time, everyone else can settle with something profound that they are passionate about, so many will die and leave a lot of half-pursued interests for their beneficiaries to plough through (how come your recently deceased uncle got a bongo drum next to a Raspberry Pi?). 

Thoughts of shallow engagements and half-complete hobbies might be a sign of high intelligence and giftedness.

Maybe to be blessed, you need to be an imbecile.


Saturday, November 30, 2024

Make Investing Great Again !


Let's discuss the US elections objectively when things calm down. This time around, I was less keen to see a Republican victory because I thought that Trump would acquiesce to Putin and bring tremendous suffering to Ukrainian civilians. Still, after reading some analysis, I don't know if Biden's vacillation and giving Ukrainians just enough to hold back the Russians is now a good idea. According to the Economist, the latest projection is that 2025 may see fighting cease at least once, which might be suitable for preserving lives. There will be some unhappiness that Putin will get to keep 20% of Ukraine, but there's a chance Ukraine is free to join the EU. 

So this now makes me ambivalent or even rather happy with a Trump victory!

Let's first look at how investors can tilt their portfolios. This central idea is that tariffs and deporting immigrants will exacerbate inflation in the US, so interest rates may be kept higher for much longer. This would be bullish for local banks but bearish for REITs. However, to what extent can Trump implement these policies? There are still some old-school fiscal conservatives amongst the American leadership, so I don't think an all-in strategy for local banks is a good idea. There has to be a mix between banks and REITs, and I prefer REITs right now, as REITs are the less popular investment choice. My pick is to go with the REITs with the lowest betas, in case the investor might be wrong. 

Hopefully, by year-end, I can pick up some high-dividend SDRs to diversify my dividends further from my usual CDP holdings. However, I'd like to know whether these SDRs will pay dividends on the payout date. I'm still quite old school and prefer to have my more static holdings under CDP because the money arrives in the bank account even if you are in a coma in a hospital. Only some enjoy waiting for the dividends to be credited into your custodian broker account, which requires a manual step to withdraw the funds. You feel less rich this way.

At the international stage, my trend-following algorithm is performing as projected by backtests, racking close to 20% gains in about 16 months. Trending ETFs are mainly US equities, gold, and crypto, but the algorithm miscalculated and was whiplashed by China tech, although losses are minimal. 

I won't talk solely about investing in the Trump era—given how unpredictable US politics will be, I'm likely to be wrong anyway.

By now, we have a clearer idea of why Trump won. 

The first reason is that despite no recession, Americans feel poor thanks to inflation. Flat-footed economists call this a vibecession. Like in Singapore, families are dealing with larger mortgage payments and lower amounts for discretionary spending. Almost everyone is out of the country, so you can feel richer in JB or even Kyoto, Japan. I spent more than $100 on movie tickets here this week. 

The second reason is a massive backlash against the woke ideology that Kamala stands for. You can feel it here in Singapore. Almost every middle-aged guy here is unhappy with identity politics in Marvel movies and computer games. Games like Concord and Dragon Age: Veilguard angered not just white male gamers in the US. I have gamers here ranting and raving about it. 

Elon Musk knew something when he gave a speech referring to "incremental political science majors" as the target of all this hatred. This resonated with my engineer identity during my working days when any work that had to be referred to the legal department would somehow delay my project or end up doubling the workload - after a vicious dressing down from an effete but legally trained bureaucrat soy boy. You want to punch that guy's face in, but you can't, so you build up a dividends portfolio instead and then find out how this bastard was trained. 

(Marvel should do my origin story.)

So, I'm very familiar with the kind of blue-collar anger in the US. You do the hard work, maybe build up a small business. Then these tenured social science humanities types start to label you a bigot from their ivory towers, then even want your video game character to do 10 push-ups when you misgender someone. 

Yes, logically, these assholes are all different people. Still, to some blue-collar conservative workers, they are all one person -  the humanities goth-blue-haired land whale feminist Marxist scum who want to defund the police - represented by a Democrat president elect.

Wouldn't you want to vote for Trump, too?

Following the new politics is now giving us older gamers a massive pay-off.

I look forward to hearing the screams of the blue-haired land whales that pollute the RPG space in Singapore if Elon Musk buys Hasbro and owns the D&D brand.

That will make me return to regular gaming because I know the exact kind of DM that spouts unnecessary anti-PAP slogans before a game. After all, somehow, to them, PAP is neo-liberals.

I will tell him: 

Opposition is for they/them. PAP is for you!


Sunday, November 24, 2024

Hobbies Update : Thank you for reaching out guys!


This might be a rambling post, but I'd first like to thank the readers and old pals who connected with me over the past week; as an extrovert, the conversations kept me sane, and I could enjoy myself while my family was touring Taiwan. My social diary was so active I could not start watching the DanDaDan anime, and I could not even download a single game from Steam, so this affected my hobbies, but I generally prioritise personal connections over games.

But I want to talk about one more thing before I run down the hobbies that I have at the moment. Recently, there's been some insight into the fact that ageing occurs in bursts. We tend to age a lot when we reach 44 years old, 60 years old, and then another burst at 78 years old. The effect is that those who reach 44 will have problems with their metabolic rate and might not be able to purge caffeine as quickly as before. Another impact from other sources is that our neurons fire less frequently, so we will find that time passes faster. These insights are recent, and I would probably not go for a third degree if I knew that my mind would slow down when I graduate. But all this will affect the way I view my hobbies moving forward.

Ok, let's rundown what stays and what goes:

a) Reading

Reading is so powerful that it is the hobby most women find attractive on dating apps, but to be fair, most of the stuff I read is not friendly to women. I have read a lot about finance, business, and self-help; there is nothing for me every year at the Singapore Writer's Festival. But as I slow down, I am now more open to more profound and shorter self-reflective books. In fact, every December, I will have a moratorium on non-fiction books to mop up books on gaming history, Japanese fiction, and the latest Korean genre of healing literature. 

Reading healing fiction is weirdly practical because it addresses all the post-retirement identity issues that FIRE folks experience. 

I also have a new hobby, I'm now a book scavenger at the book drops in major regional libraries, and I'm always hunting for old books discarded by other Singaporeans. 

b) PC Gaming

I'm no longer a PC gamer. I will wake up to something like Baldur's Gate 3 that lets me experiment with weird D&D character builds, but otherwise, it will not play a role in my life anymore. But I love following the politics behind gaming, where gatekeepers are waging war against developers who are incorporating Woke and DEI values into franchises people love. I'm clearly on the side of the gatekeepers because I don't like getting lectured for having conservative values, so I sincerely enjoyed reading about the substantial business losses suffered by games like Concord and Dragon Age Veilguard.

I will be willing to get into games if I can convince my son to enjoy them with me. It's hard because he is 8, so the best he can do is assemble some simple Gunpla. I'm checking to see if I can get him into Warhammer 40k, paint some minis, and then roll some dice—anything is a lesser evil than brain rot from TikTok or YouTube. 

My peers have yet to successfully share a hobby with their kids, but I still want to try. 

c) Board, TCG and RPG gaming

Some old friends from my secondary school caught up with me, and we agreed to play the games we'd slowly collected over the past. However, we needed help finding folks to play with us. These are reasonably complicated games like Dune Boardgame, Legend of the 5 Rings LCG, and Battletech. If we can get a group of about 5, I promise to run D&D 2024 for them regularly. 

I was lucky because I doubted I could fit serious gaming into my life if I could not monetise it. But I game in my neighbourhood in Woodlands, so things might work out this time. 

Regardless of what game I play, I play the same way I play RPGs. I'm constantly on the attack and will recklessly charge someone if I know the rules. I don't believe in or engage in diplomacy. In L5R, I only play the Lion Clan. For Magic the Gathering, I only play black/red cards. In Battletech... I only know... DEATH FROM ABOVE!

I'm fun to play with because I tend to lose a lot. 

Thank goodness I don't invest like the way I game.

d) Trips to Johor

This isn't a hobby, but I might have more friends who can hit JB with me on a weekday to escape the cost of living in Singapore. Yesterday, I attempted to strike a fantastic chicken chop restaurant called It Roo near City Square. Then, I went to Aeon Tebrau to visit Tsutaya Bookstore before heading to a pasar malam at Tun Aminah. Now, I'm asking friends and relatives to devise a plan for Bukit Indah as we attempt a different crossing from Tuas.  

Sometimes, we are defined by what we don't do for hobbies. I no longer care about watching shows. If Disney produces more woke series like The Acolyte, I will cancel my subscription. I no longer buy comics for the same reason. I also watch fewer movies because Marvel is rethinking how to do superhero shows.